Japanese conglomerate tells PM Tarique Rahman it aims to begin work on a hybrid electric vehicle plant in an economic zone in 2027
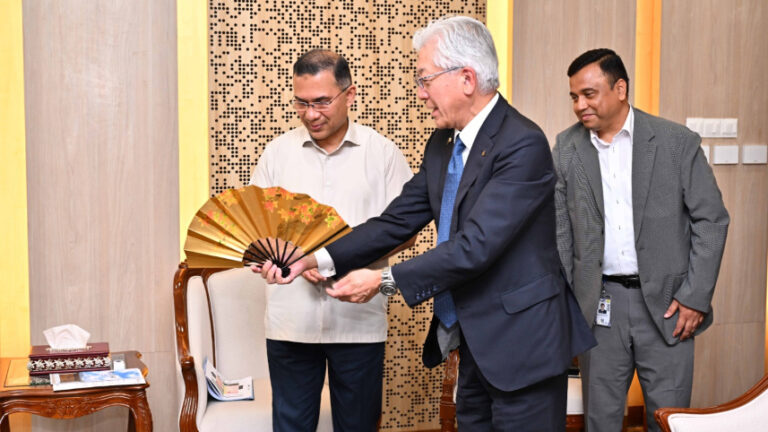
Toyota Tsusho Corporation is exploring plans to manufacture vehicles in Bangladesh, with a high-level delegation from the Japanese company briefing Prime Minister Tarique Rahman on its proposed investment on Tuesday.
The delegation, led by Toyota Tsusho Vice Chairman Ichiro Kashitani, met the prime minister at his office in the Secretariat and informed him of the company’s plan to establish a Toyota vehicle manufacturing plant in Bangladesh, said PM’s Deputy Press Secretary Shahadat Hossain Shadhin.
loyment generation, industrialisation expansion, technology transfer, and the development of skilled human resources in the country.
The two sides also discussed expanding Toyota’s operations in Bangladesh, potential investment opportunities, and the company’s long-term business plans.
Tarique welcomed Toyota Tsusho’s interest in expanding its investment and operations in Bangladesh.
He said the government is working to ensure a stable, competitive, and investment-friendly environment for both domestic and foreign investors.
The prime minister said the government is committed to providing necessary policy support, infrastructure facilities, and other opportunities to foreign investors.
He also highlighted the potential of waste-to-energy and renewable energy in Bangladesh, saying the government will provide necessary support if Toyota Tsusho is interested in investing in these sectors.
The Toyota delegation said its plan to expand Toyota Bangladesh’s distribution network to all divisional cities is already underway.
The expansion is aimed at making Toyota’s services and operations more accessible across the country.
The company also informed the prime minister that Toyota Bangladesh will begin work in 2027 to establish a Hybrid Electric Vehicle (HEV) manufacturing industry in an economic zone under the development vision of “With Bangladesh, for Bangladesh”, with full-scale production targeted for 2029.
Toyota also expressed interest in contributing to human resources development in Bangladesh, particularly by creating technical and vocational training opportunities for young people, enhancing their skills and developing a workforce suited to future industries.
Commerce Minister Khandakar Abdul Muktadir, Prime Minister’s Adviser on Finance and Planning Rashed Al Mahmud Titumir, State Minister for Foreign Affairs Humaiun Kobir, Prime Minister’s Adviser on Science and Technology Rehan Asif Asad, and Prime Minister’s Special Assistant for Overseas Employment Affairs in the Asia-Pacific Region Md Shakirul Islam Khan, among others, attended the meeting.
Toyota Tsusho Mobility Division CEO Shigeru Harada, President of Toyota Bangladesh Ltd Premmit Singh and other senior officials of the company were also present.
Toyota Tsusho is the trading arm of the Toyota Group, which includes Toyota Motor and auto parts maker DENSO.
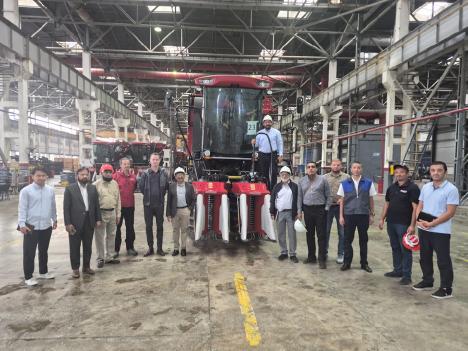
A delegation of Pakistani cotton experts witnessed a demonstration of a new 2-row cotton picker by Case New Holland (CNH) in Tashkent, Uzbekistan, generating considerable interest in the potential of mechanized cotton harvesting for Pakistan.
Cotton production in Pakistan is facing increasing challenges, including pest attacks associated with excessive humidity, labor shortages, climate change, adulterated pesticides, and low-vigor seed. Mechanization of cotton harvesting is therefore being considered as one of the potential solutions to address some of these challenges.
The CNH cotton picker demonstrated in Tashkent is a self-propelled 2-row machine equipped with a dual-side picking system. It has an average productivity of 1.33 tons per hour, with a reported picking efficiency of 90–95 percent. The machine’s row spacing is compatible with Pakistan’s prevailing cotton sowing pattern of 76 cm, while the spacing can be adjusted to 76, 81, 90 and 100 cm.
The Pakistani delegation also participated in a classroom discussion following the field demonstration, where technical and agronomic aspects of mechanized cotton harvesting were discussed.
The delegation comprised Dr. Zahid Mahmood, Former Cotton Commissioner; Mr. Muhammad Jameel, Director, Cotton Research Institute (CRI), Multan; Mr. Yasir Jan Khan, a leading cotton grower; Dr. Alamgir Khan, Mechanization Expert; and Engr. Adnan Iqbal from Farm3vo Technologies (Pvt.) Ltd (A company of AlKaram group) CNH distributor in Pakistan.
Addressing the participants, Dr. Zahid said that Pakistan has the capability to develop and provide a cotton variety suitable for mechanical harvesting, particularly a variety that can be harvested effectively in a single picking.
Representatives of Case New Holland, including Mr. Wojciech Purczynski; Mr. Sala Massimiliano; Engr. Mansoor Rizvi, CNH Country Manager, Pakistan; BURKHANOV Oybek and Mr. Hall Brian, briefed the Pakistani delegation on the machine’s technical features and its potential benefits for Pakistan’s cotton crop.
The visit provided an opportunity for Pakistani cotton experts to assess the suitability of mechanized cotton harvesting under local crop conditions and to exchange views with CNH specialists on the prospects and challenges of introducing cotton-picking technology in Pakistan.
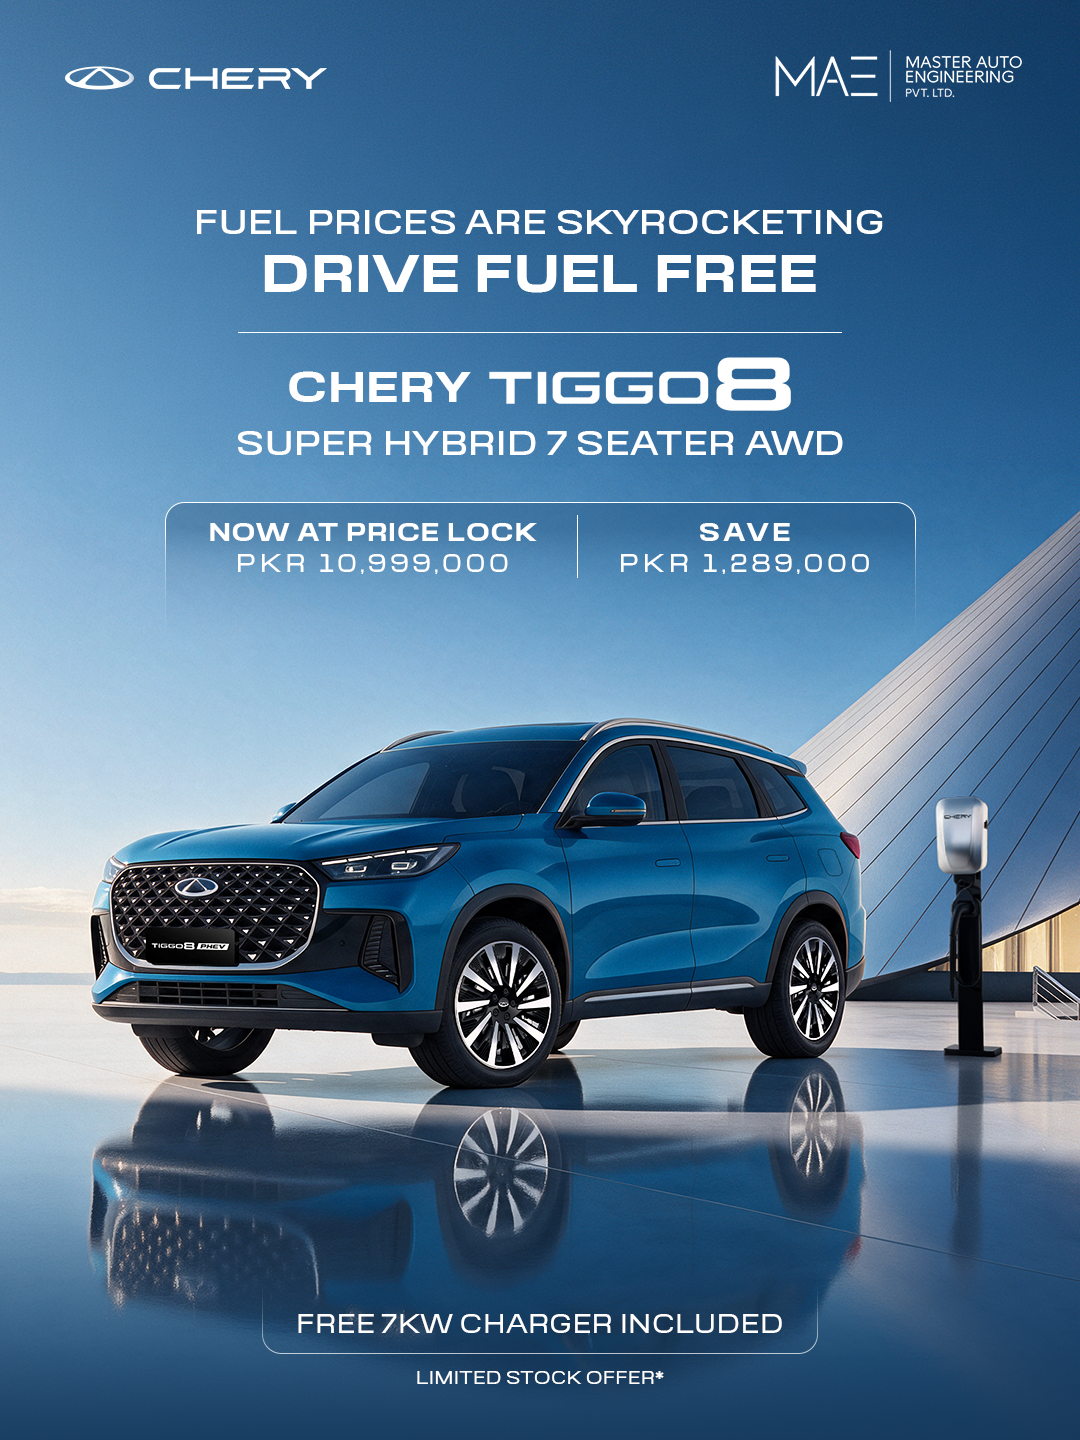
Chery Master Offers PKR 1.29 Million Upfront Savings on Tiggo 8 Super Hybrid AWD
Limited Stock Price Lock Offer with a complimentary 7 kW Home Charger worth PKR 100,000
KARACHI, October 9 2026: Chery Master Pakistan is giving customers more than just a better way to drive. The Chery Tiggo 8 Super Hybrid is Pakistan’s best-value 7-seater plug-in hybrid SUV, combining AWD capability, six driving modes, premium comfort, advanced technology and strong performance. With the applicable sales tax on PHEVs nearly doubling, the Chery Tiggo 8 Super Hybrid is now available at PKR 10,999,000 against its original price of PKR 12,289,000, giving customers an upfront saving of PKR 1.29 million under the Limited Stock Price Lock Offer. The offer also includes a complimentary 7 kW home charger worth PKR 100,000, adding further value from day one.
The biggest saving comes every time you drive.
Fuel has become one of the biggest ongoing costs of owning a car in Pakistan. With petrol prices approaching PKR 400 per litre, a comparable petrol car averaging around 8 km/l can consume approximately PKR 100,000 in fuel every month for a 2,000-kilometre monthly drive, translating into nearly PKR 1 million in fuel costs over 20,000 km.
This is Fuel Anxiety: the cost and uncertainty that comes with every kilometre driven.
The Chery Tiggo 8 Super Hybrid offers a different way forward. Powered by Chery Super Hybrid (CSH), its plug-in hybrid system combines electric driving for everyday mobility with petrol flexibility for longer journeys, allowing customers to reduce fuel dependency without giving up the SUV they want.
With up to 90 kilometres of pure electric range and a combined range of around 1,200 kilometres, the Chery Tiggo 8 Super Hybrid operates as an electric-priority vehicle, enabling most daily driving without fuel while retaining the flexibility needed for longer journeys. And for customers with solar at home, the energy already being generated on their rooftop can power their everyday electric driving, turning their solar investment into mobility.
As Pakistan’s only 7-seater plug-in hybrid D-SUV, it brings three full rows of seating into the PHEV category, giving customers the space to bring the whole family along in one car, without needing an additional vehicle and another fuel bill.
Its performance matches its capability, with 496 horsepower, 735 Nm of torque and 0–100 km/h in just 6.8 seconds, making it one of the most powerful SUVs in the D segment.
Inside, the Chery Tiggo 8 Super Hybrid is one of the most feature-rich SUVs in its class, with a Queen Co-Pilot zero-gravity massage seat, heated and ventilated front seats, 15.6-inch HD infotainment display, digital instrument cluster, 12-speaker Sony premium audio system and immersive ambient lighting.
Chery ranks No. 1 among Chinese brands in J.D. Power in Quality. The Tiggo 8 Super Hybrid also carries a 5-star global safety rating, with 10 airbags, 23+ active safety features and Level 2 ADAS, alongside Euro 6B compliance.
You don’t have to give up the SUV you want to escape the fuel bill. You can change what powers it.
Introduced through Master Auto Engineering, part of Master Group, in partnership with Chery Automobile, China’s No. 1 automotive exporter for 23 consecutive years.
Backed by Master Group’s 60+ years of legacy and 40+ years in automotive, Chery Master Pakistan is building the next chapter of New Energy mobility in Pakistan. With 14 fully operational 3S dealerships across Pakistan and plans to expand to 20 by 2027, Chery Master is rapidly expanding nationwide access and after-sales support for its growing customer base.
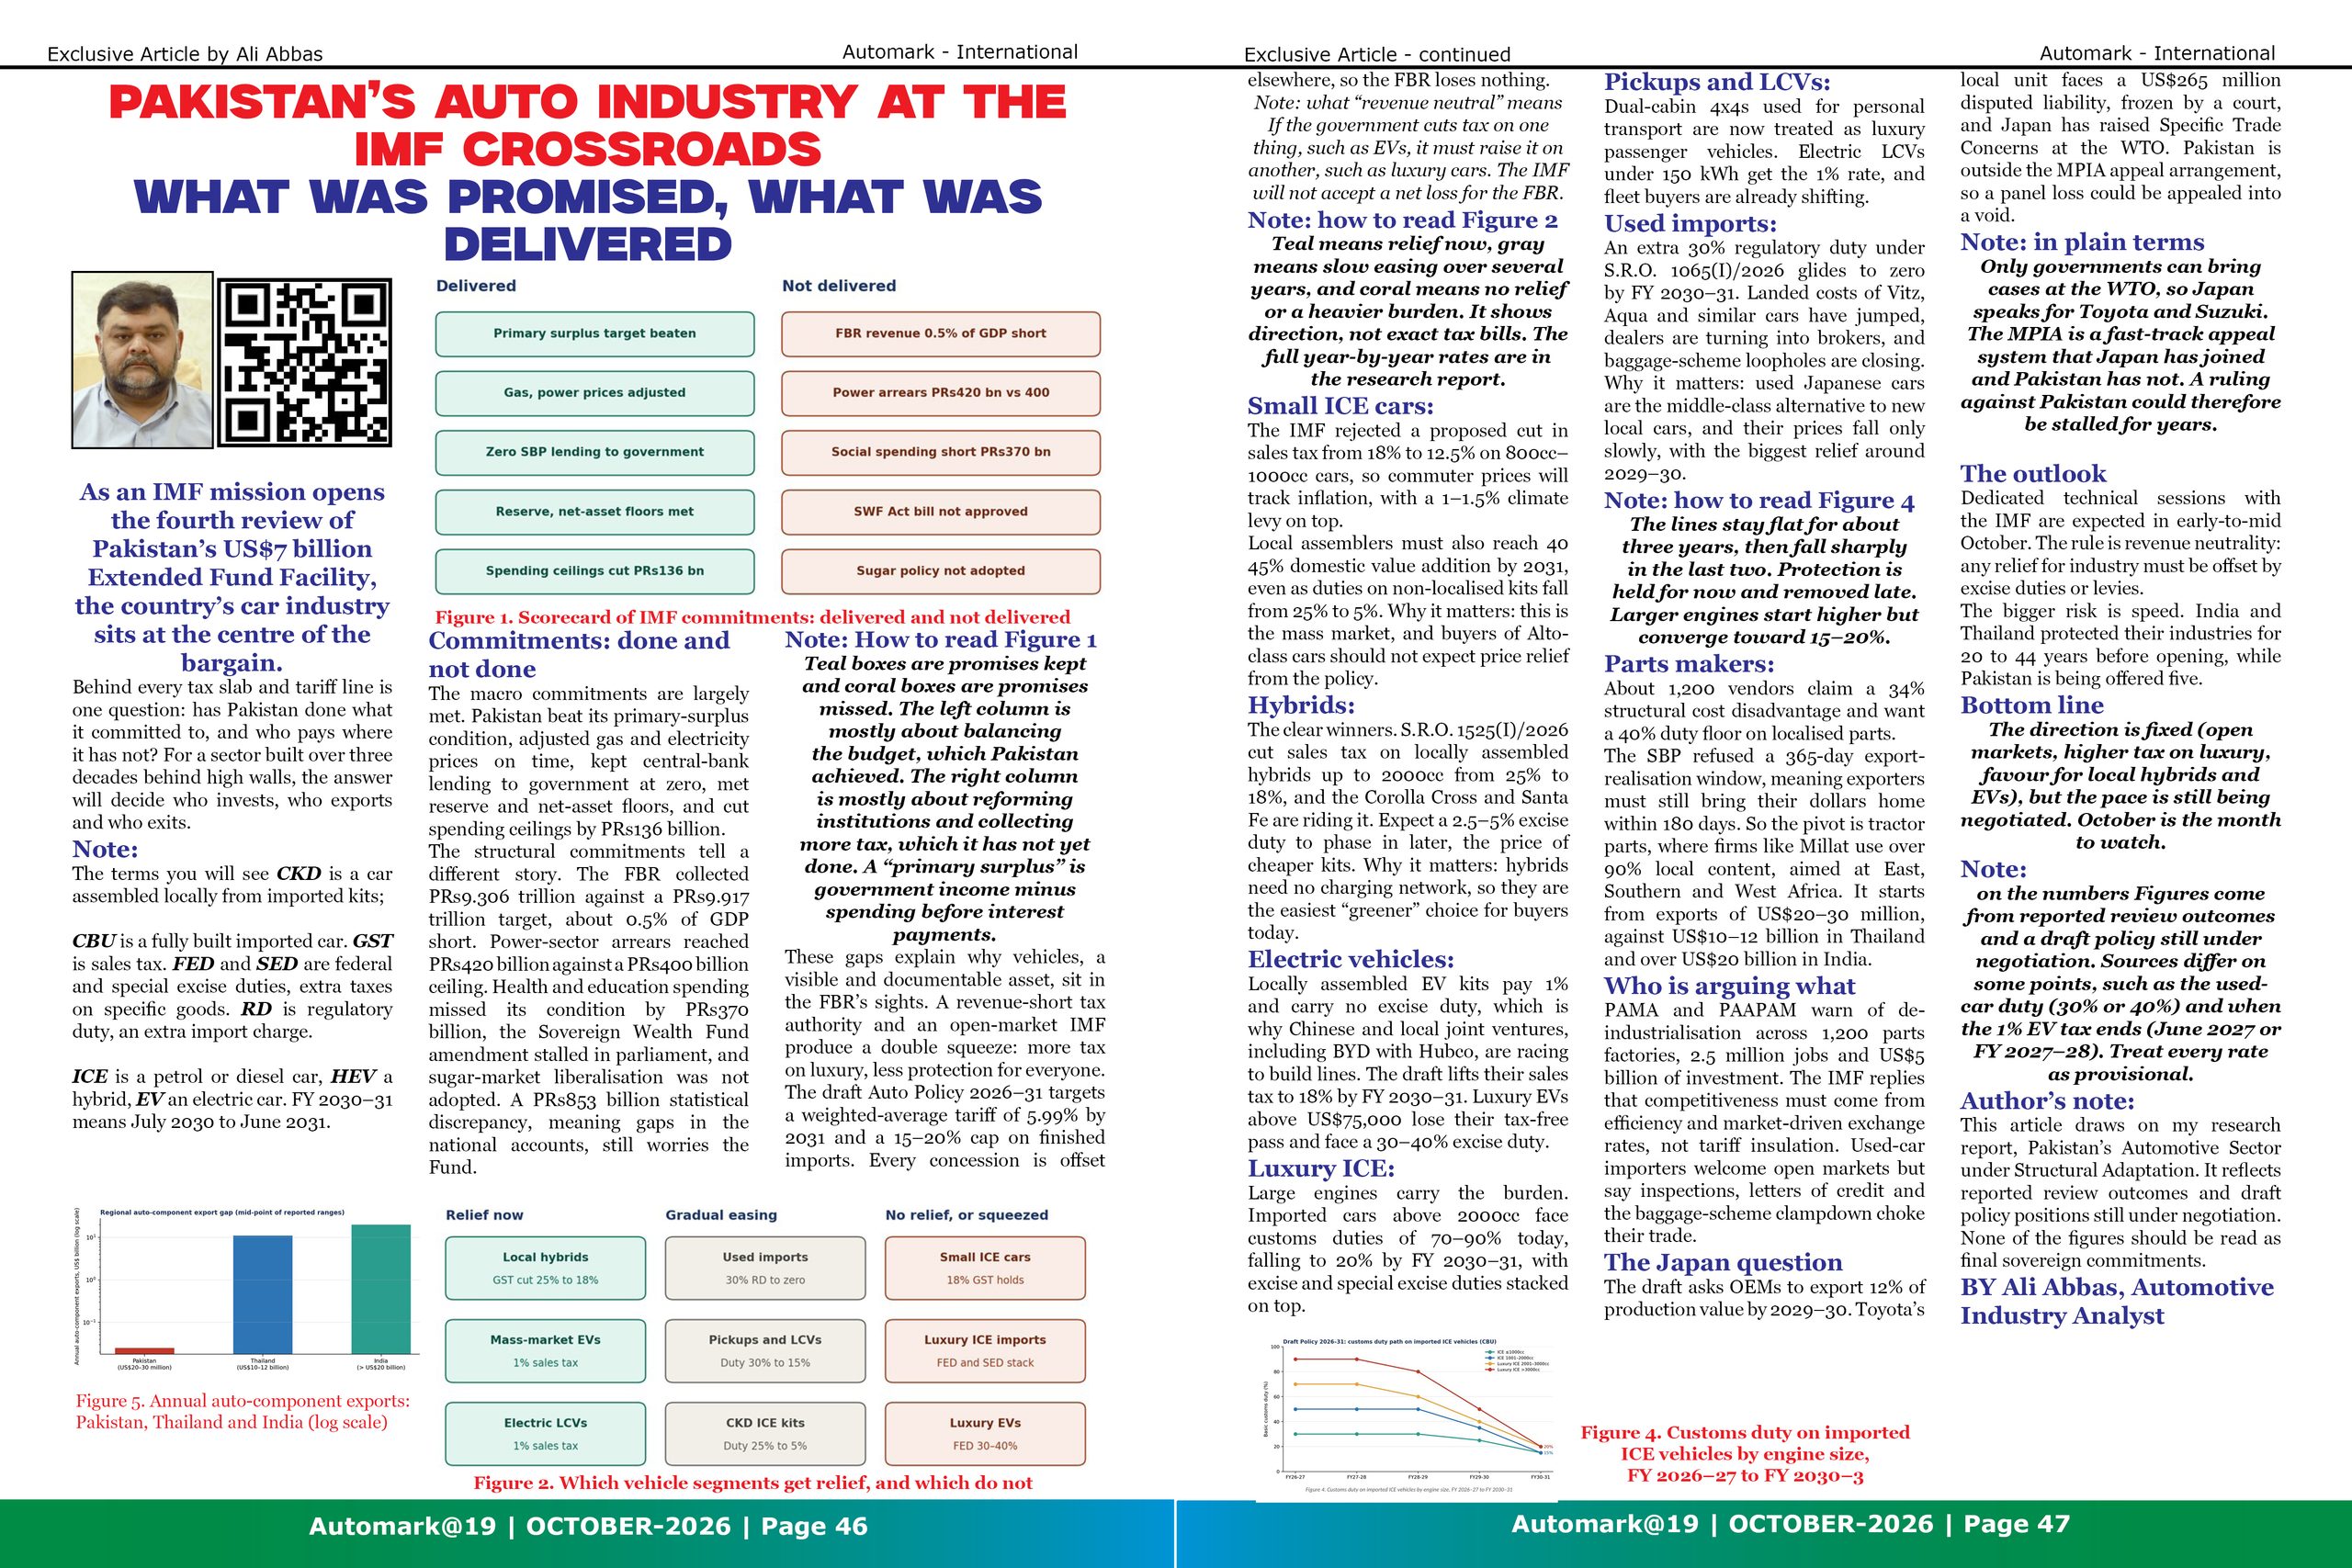
As an IMF mission opens the fourth review of Pakistan’s US$7 billion Extended Fund Facility, the country’s car industry sits at the centre of the bargain. Behind every tax slab and tariff line is one question: has Pakistan done what it committed to, and who pays where it has not? For a sector built over three decades behind high walls, the answer will decide who invests, who exports and who exits.
Note: the terms you will see CKD is a car assembled locally from imported kits; CBU is a fully built imported car. GST is sales tax. FED and SED are federal and special excise duties, extra taxes on specific goods. RD is regulatory duty, an extra import charge. ICE is a petrol or diesel car, HEV a hybrid, EV an electric car. FY 2030–31 means July 2030 to June 2031.
Commitments: done and not done
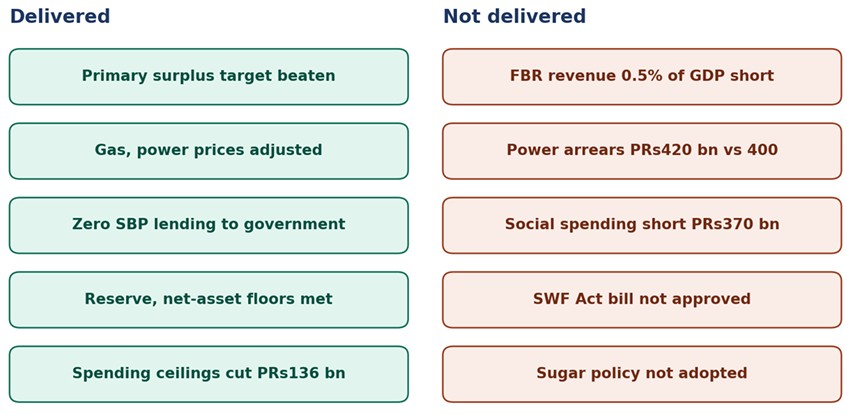
The macro commitments are largely met. Pakistan beat its primary-surplus condition, adjusted gas and electricity prices on time, kept central-bank lending to government at zero, met reserve and net-asset floors, and cut spending ceilings by PRs136 billion.
The structural commitments tell a different story. The FBR collected PRs9.306 trillion against a PRs9.917 trillion target, about 0.5% of GDP short. Power-sector arrears reached PRs420 billion against a PRs400 billion ceiling. Health and education spending missed its condition by PRs370 billion, the Sovereign Wealth Fund amendment stalled in parliament, and sugar-market liberalisation was not adopted. A PRs853 billion statistical discrepancy, meaning gaps in the national accounts, still worries the Fund
Note: how to read Figure 1
Teal boxes are promises kept and coral boxes are promises missed. The left column is mostly about balancing the budget, which Pakistan achieved. The right column is mostly about reforming institutions and collecting more tax, which it has not yet done. A “primary surplus” is government income minus spending before interest payments.
These gaps explain why vehicles, a visible and documentable asset, sit in the FBR’s sights. A revenue-short tax authority and an open-market IMF produce a double squeeze: more tax on luxury, less protection for everyone. The draft Auto Policy 2026–31 targets a weighted-average tariff of 5.99% by 2031 and a 15–20% cap on finished imports. Every concession is offset elsewhere, so the FBR loses nothing.
Note: what “revenue neutral” means
If the government cuts tax on one thing, such as EVs, it must raise it on another, such as luxury cars. The IMF will not accept a net loss for the FBR
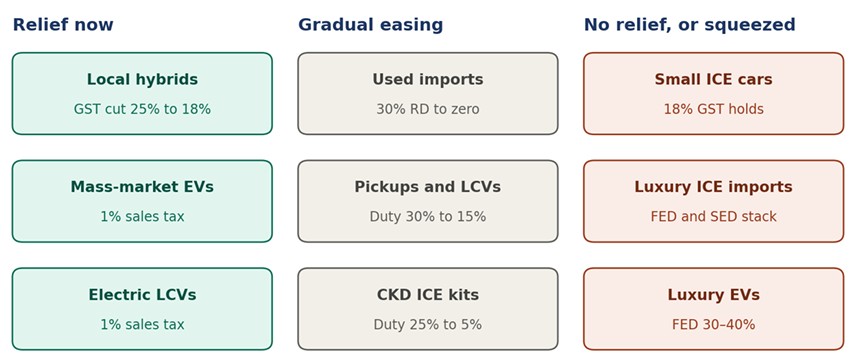
Note: how to read Figure 2
Teal means relief now, gray means slow easing over several years, and coral means no relief or a heavier burden. It shows direction, not exact tax bills. The full year-by-year rates are in the research report.
Small ICE cars. The IMF rejected a proposed cut in sales tax from 18% to 12.5% on 800cc–1000cc cars, so commuter prices will track inflation, with a 1–1.5% climate levy on top. Local assemblers must also reach 40 45% domestic value addition by 2031, even as duties on non-localised kits fall from 25% to 5%. Why it matters: this is the mass market, and buyers of Alto-class cars should not expect price relief from the policy.
Hybrids. The clear winners. S.R.O. 1525(I)/2026 cut sales tax on locally assembled hybrids up to 2000cc from 25% to 18%, and the Corolla Cross and Santa Fe are riding it. Expect a 2.5–5% excise duty to phase in later, the price of cheaper kits. Why it matters: hybrids need no charging network, so they are the easiest “greener” choice for buyers today.
Electric vehicles. Locally assembled EV kits pay 1% and carry no excise duty, which is why Chinese and local joint ventures, including BYD with Hubco, are racing to build lines. The draft lifts their sales tax to 18% by FY 2030–31. Luxury EVs above US$75,000 lose their tax-free pass and face a 30–40% excise duty.
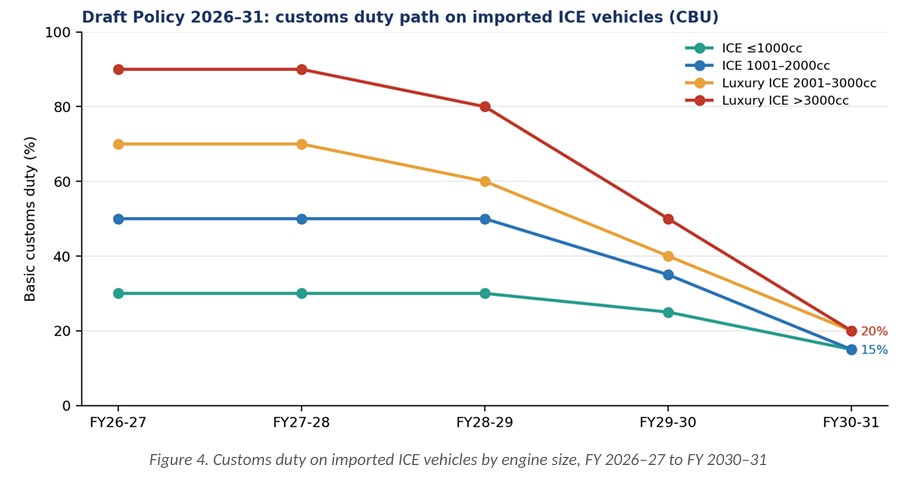
Luxury ICE. Large engines carry the burden. Imported cars above 2000cc face customs duties of 70–90% today, falling to 20% by FY 2030–31, with excise and special excise duties stacked on top.
Pickups and LCVs. Dual-cabin 4x4s used for personal transport are now treated as luxury passenger vehicles. Electric LCVs under 150 kWh get the 1% rate, and fleet buyers are already shifting.
Used imports. An extra 30% regulatory duty under S.R.O. 1065(I)/2026 glides to zero by FY 2030–31. Landed costs of Vitz, Aqua and similar cars have jumped, dealers are turning into brokers, and baggage-scheme loopholes are closing. Why it matters: used Japanese cars are the middle-class alternative to new local cars, and their prices fall only slowly, with the biggest relief around 2029–30.
Note: how to read Figure 4 The lines stay flat for about three years, then fall sharply in the last two. Protection is held for now and removed late. Larger engines start higher but converge toward 15–20%.
Parts makers. About 1,200 vendors claim a 34% structural cost disadvantage and want a 40% duty floor on localised parts. The SBP refused a 365-day export-realisation window, meaning exporters must still bring their dollars home within 180 days. So the pivot is tractor parts, where firms like Millat use over 90% local content, aimed at East, Southern and West Africa. It starts from exports of US$20–30 million, against US$10–12 billion in Thailand and over US$20 billion in India.
Who is arguing what PAMA and PAAPAM warn of de-industrialisation across 1,200 parts factories, 2.5 million jobs and US$5 billion of investment. The IMF replies that competitiveness must come from efficiency and market-driven exchange rates, not tariff insulation. Used-car importers welcome open markets but say inspections, letters of credit and the baggage-scheme clampdown choke their trade.
The Japan question The draft asks OEMs to export 12% of production value by 2029–30. Toyota’s local unit faces a US$265 million disputed liability, frozen by a court, and Japan has raised Specific Trade Concerns at the WTO. Pakistan is outside the MPIA appeal arrangement, so a panel loss could be appealed into a void.
Note: in plain terms only governments can bring cases at the WTO, so Japan speaks for Toyota and Suzuki. The MPIA is a fast-track appeal system that Japan has joined and Pakistan has not. A ruling against Pakistan could therefore be stalled for years.
The outlook
Dedicated technical sessions with the IMF are expected in early-to-mid October. The rule is revenue neutrality: any relief for industry must be offset by excise duties or levies.
The bigger risk is speed. India and Thailand protected their industries for 20 to 44 years before opening, while Pakistan is being offered five.
Bottom line The direction is fixed (open markets, higher tax on luxury, favour for local hybrids and EVs), but the pace is still being negotiated. October is the month to watch.
Note: on the numbers Figures come from reported review outcomes and a draft policy still under negotiation. Sources differ on some points, such as the used-car duty (30% or 40%) and when the 1% EV tax ends (June 2027 or FY 2027–28). Treat every rate as provisional.
Author’s note This article draws on my research report, Pakistan’s Automotive Sector under Structural Adaptation. It reflects reported review outcomes and draft policy positions still under negotiation. None of the figures should be read as final sovereign commitments. — Ali Abbas, Automotive Industry Analyst
This exclusive article has been published in Automark’s October-2026 printed and digital edition.
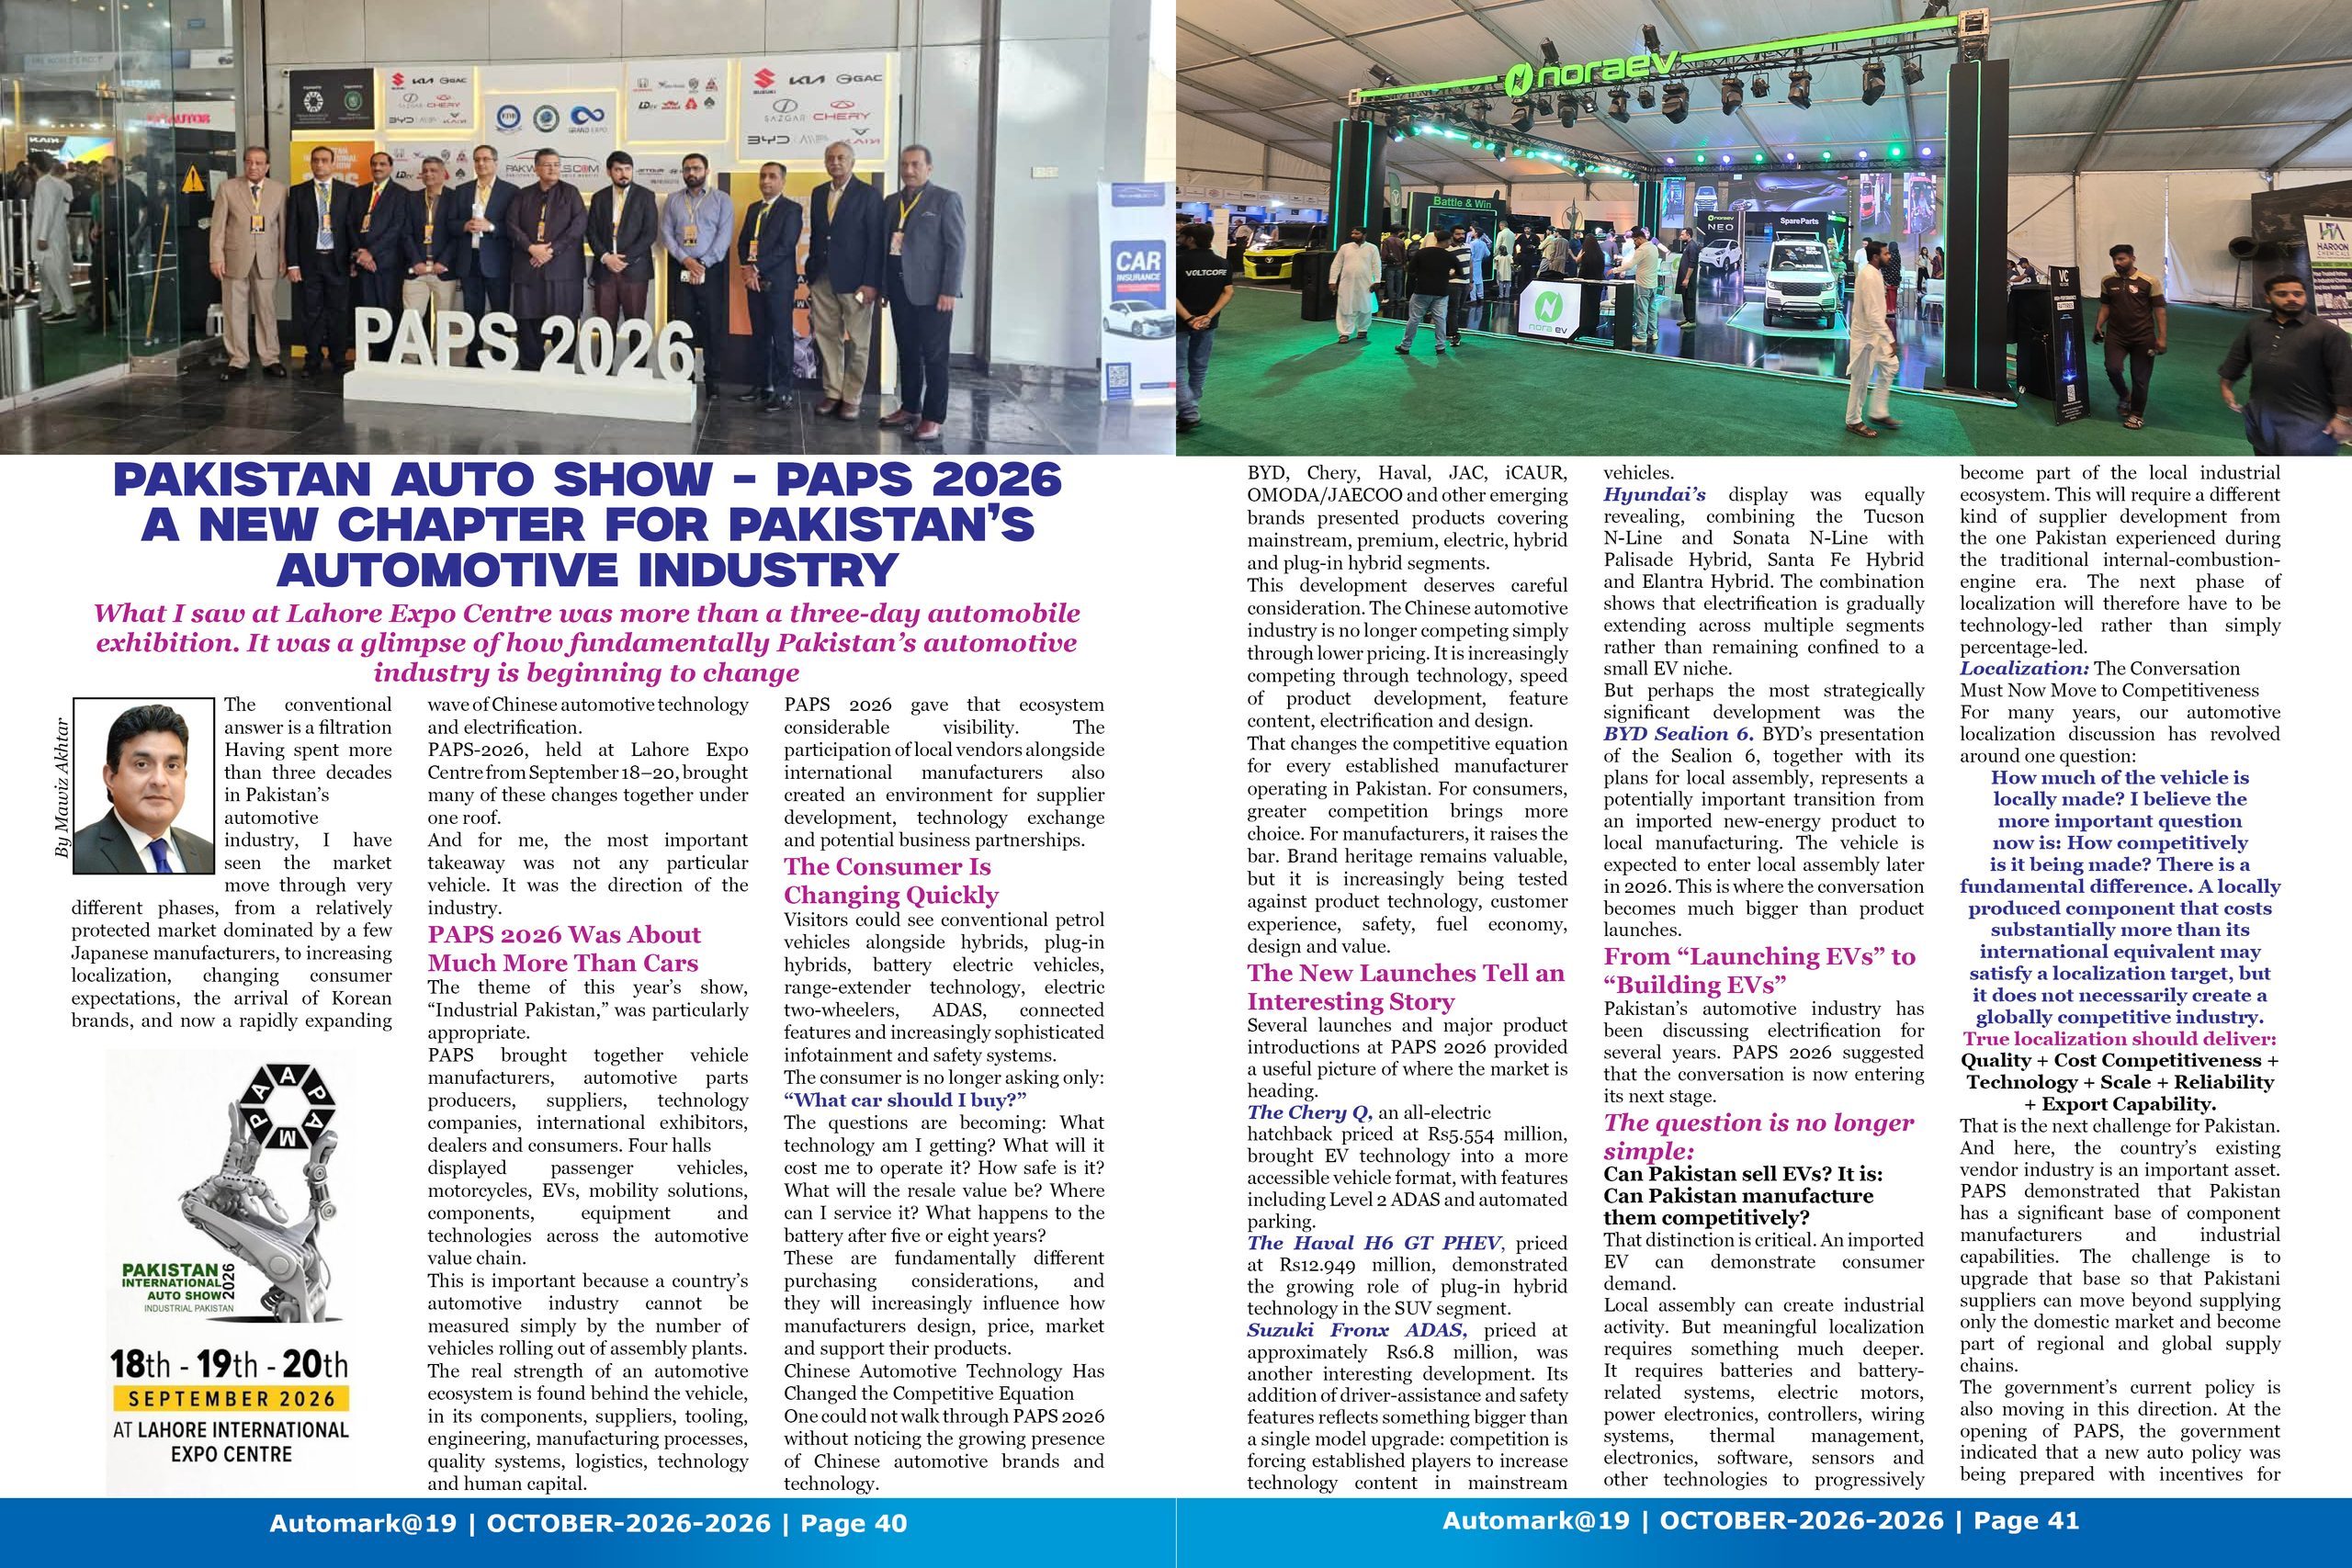
What I saw at Lahore Expo Centre was more than a three-day automobile exhibition. It was aglimpseofhowfundamentallyPakistan’sautomotiveindustryisbeginningtochange.
Having spent more than three decades in Pakistan’s automotive industry, I have seen the market move through very different phases, from a relatively protected market dominated by a few Japanese manufacturers, to increasing localization, changing consumer expectations, the arrival of Korean brands, and now a rapidly expanding wave of Chinese automotive technology and electrification.
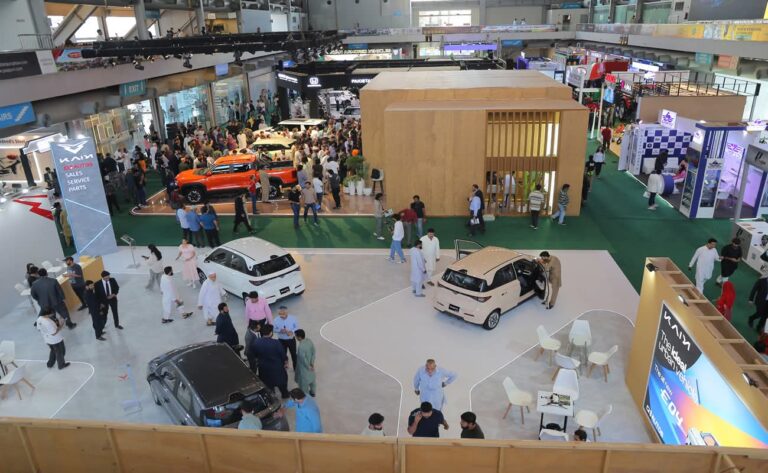
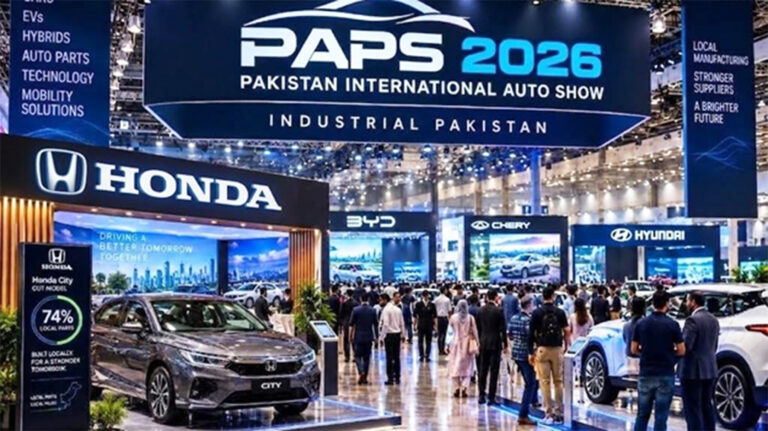
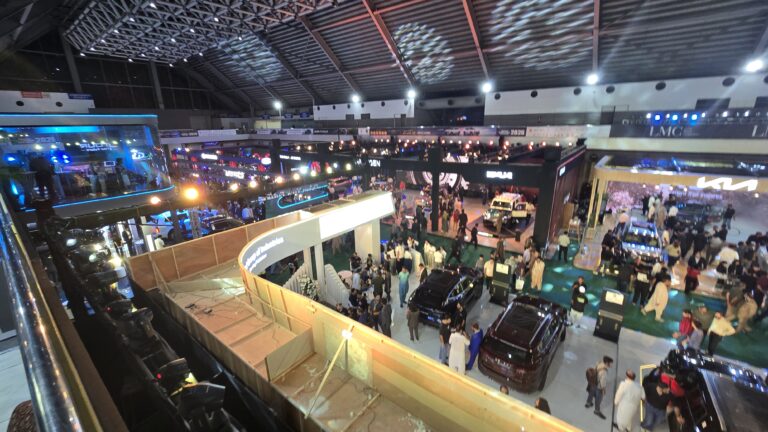
The Pakistan International Auto Show (PAPS) 2026, held at Lahore Expo Centre from September 18–20, brought many of these changes together under one roof.
And for me, the most important takeaway was not any particular vehicle. It was the direction of the industry.
PAPS 2026 Was About Much More Than Cars
The theme of this year’s show, “IndustrialPakistan,” was particularly appropriate.
PAPS brought together vehicle manufacturers, automotive parts producers, suppliers, technology companies, international exhibitors, dealers and consumers. Four halls
displayed passenger vehicles, motorcycles, EVs, mobility solutions, components, equipment and technologies across the automotive value chain.
This is important because a country’s automotive industry cannot be measured simply by the number of vehicles rolling out of assembly plants.
The real strength of an automotive ecosystem is found behind the vehicle, in its components, suppliers, tooling, engineering, manufacturing processes, quality systems, logistics, technology and human capital.
PAPS 2026 gave that ecosystem considerable visibility. The participation of local vendors alongside international manufacturers also created an environment for supplier development, technology exchange and potential business partnerships. The involvement of SMEDA as a strategic partner further underlined the importance of integrating SMEs into the industrial value chain. That, in my view, is one of the most encouraging aspects of this year’s show.
The Consumer Is Changing Quickly
Perhaps the most striking difference from the auto shows of the past was the sheer diversity of technology on display.
Visitors could see conventional petrol vehicles alongside hybrids, plug-in hybrids, battery electric vehicles, range-extender technology, electric two-wheelers, ADAS, connected features and increasingly sophisticated infotainment and safety systems.
The consumer is no longer asking only:
“What car should I buy?”
The questions are becoming: What technology am I getting? What will it cost me to operate it? How safe is it? What will the resale value be? Where can I service it? What happens to the battery after five or eight years?
These are fundamentally different purchasing considerations, and they will increasingly influence how manufacturers design, price, market and support their products.
Chinese Automotive Technology Has Changed the Competitive Equation
One could not walk through PAPS 2026 without noticing the growing presence of Chinese automotive brands and technology.
BYD, Chery, Haval, JAC, iCAUR, OMODA/JAECOO and other emerging brands presented products covering mainstream, premium, electric, hybrid and plug-in hybrid segments.
This development deserves careful consideration. The Chinese automotive industry is no longer competing simply through lower pricing. It is increasingly competing through technology, speed of product development, feature content, electrification and design. That changes the competitive equation for every established manufacturer operating in Pakistan. For consumers, greater competition brings more choice. For manufacturers, it raises the bar. Brand heritage remains valuable, but it is increasingly being tested against product technology, customer experience, safety, fuel economy, design and value.
The New Launches Tell an Interesting Story
Several launches and major product introductions at PAPS 2026 provided a useful picture of where the market is heading.
The Chery Q, an all-electric hatchback priced at Rs5.554 million, brought EV technology into a more accessible vehicle format, with features including Level 2 ADAS and automated parking.
The Haval H6 GT PHEV, priced at Rs12.949 million, demonstrated the growing role of plug-in hybrid technology in the SUV segment.
Suzuki Fronx ADAS, priced at approximately Rs6.8 million, was another interesting development. Its addition of driver-assistance and safety features reflects something bigger than a single model upgrade: competition is forcing established players to increase technology content in mainstream vehicles.
Hyundai’s display was equally revealing, combining the TucsonN-LineandSonataN-Line with PalisadeHybrid,SantaFeHybridandElantraHybrid. The combination shows that electrification is gradually extending across multiple segments rather than remaining confined to a small EV niche.
But perhaps the most strategically significant development was the BYD Sealion 6. BYD’s presentation of the Sealion 6, together with its plans for local assembly, represents a potentially important transition from an imported new-energy product to local manufacturing. The vehicle is expected to enter local assembly later in 2026. This is where the conversation becomes much bigger than product launches.
From “Launching EVs” to “Building EVs”
Pakistan’s automotive industry has been discussing electrification for several years. PAPS 2026 suggested that the conversation is now entering its next stage.
The question is no longer simple:
Can Pakistan sell EVs? It is: Can Pakistan manufacture them competitively?
That distinction is critical. An imported EV can demonstrate consumer demand.
Local assembly can create industrial activity. But meaningful localization requires something much deeper. It requires batteries and battery-related systems, electric motors, power electronics, controllers, wiring systems, thermal management, electronics, software, sensors and other technologies to progressively become part of the local industrial ecosystem. This will require a different kind of supplier development from the one Pakistan experienced during the traditional internal-combustion-engine era. The next phase of localization will therefore have to be technology-led rather than simply percentage-led.
Localization: The Conversation Must Now Move to Competitiveness
For many years, our automotive localization discussion has revolved around one question:
How much of the vehicle is locally made? I believe the more important question now is: How competitively is it being made? There is a fundamental difference. A locally produced component that costs substantially more than its international equivalent may satisfy a localization target, but it does not necessarily create a globally competitive industry. True localization should deliver:
That is the next challenge for Pakistan. And here, the country’s existing vendor industry is an important asset. PAPS demonstrated that Pakistan has a significant base of component manufacturers and industrial capabilities. The challenge is to upgrade that base so that Pakistani suppliers can move beyond supplying only the domestic market and become part of regional and global supply chains.
The government’s current policy is also moving in this direction. At the opening of PAPS, the government indicated that a new auto policy was being prepared with incentives for stakeholders including auto-parts manufacturers, while emphasizing export development.
At the PAAPAM symposium, the discussion centred on competitiveness, localization and electric mobility, with the government emphasizing competitive localization and technological advancement. The direction is encouraging. Execution will determine the outcome.
Perhaps the Most Encouraging Development: Exports
One of the most important developments surrounding PAPS 2026 was not a new vehicle launch at all. It was the growing evidence that Pakistan can move from local assembly towards export-oriented manufacturing.
Honda showcased a cut model of City showing 74%oflocallymanufacturedparts.
Pak Suzuki’s export of Pakistan-manufactured Alto and Every vehicles to Brunei is an important example. Reports indicate that more than 65% of the Alto’s components are locally produced.
EV, Hybrid, PHEV or REEV? Pakistan May Need All of Them
Another message from PAPS 2026 is that the future may not belong to a single technology. For Pakistan, the transition is likely to be more complex.
HEVs can reduce fuel consumption without requiring charging infrastructure.
PHEVs can provide meaningful electric driving while retaining the flexibility of a conventional engine.
BEVs offer zero tailpipe emissions and potentially lower running costs but require dependable charging infrastructure and appropriate electricity economics.
REEVs offer another possible bridge between electric driving and long-distance flexibility.
This makes Pakistan different from countries that have abundant charging infrastructure or highly developed electricity networks. Our transition will need to reflect our own economics, infrastructure, consumer behavior and industrial capabilities.
The winning technology for Pakistan will ultimately be determined not by marketing slogans but by total ownership economics and customer experience.
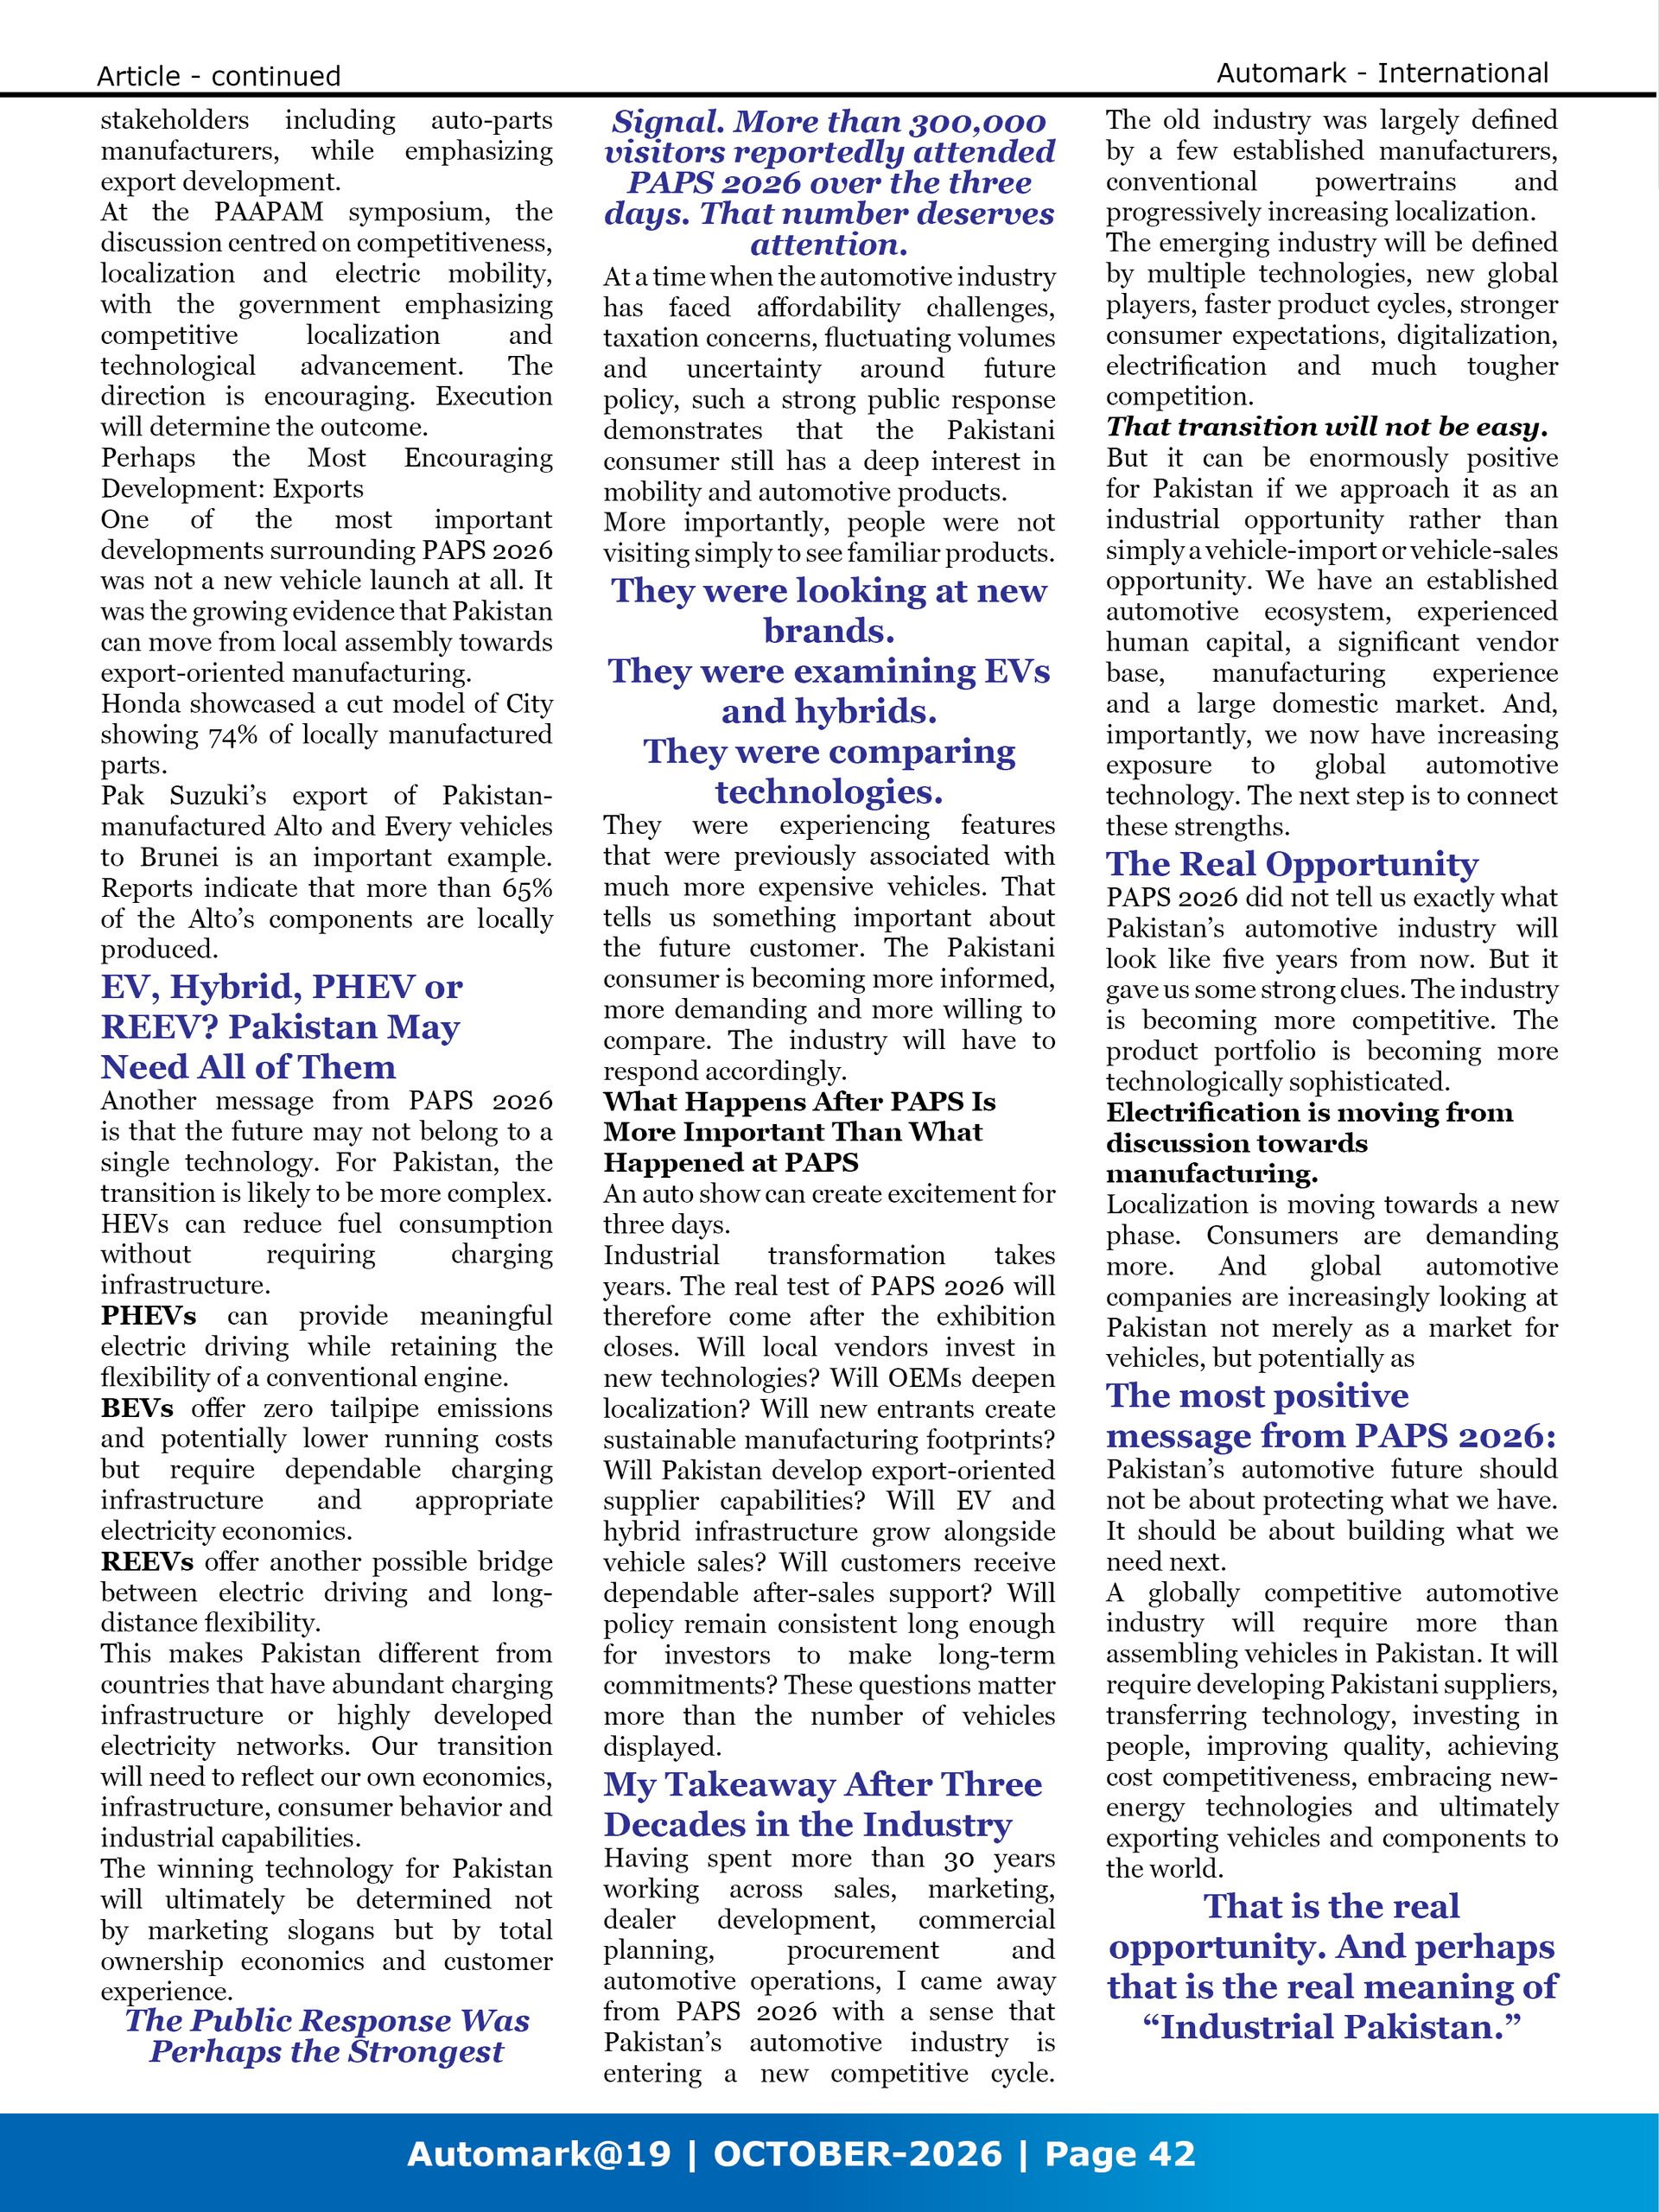
The Public Response Was Perhaps the Strongest Signal. More than 300,000 visitors reportedly attended PAPS 2026 over the three days. That number deserves attention.
At a time when the automotive industry has faced affordability challenges, taxation concerns, fluctuating volumes and uncertainty around future policy, such a strong public response demonstrates that the Pakistani consumer still has a deep interest in mobility and automotive products.
More importantly, people were not visiting simply to see familiar products.
They were looking at new brands. They were examining EVs and hybrids. They were comparing technologies. They were experiencing features that were previously associated with much more expensive vehicles. That tells us something important about the future customer. The Pakistani consumer is becoming more informed, more demanding and more willing to compare. The industry will have to respond accordingly.
What Happens After PAPS Is More Important Than What Happened at PAPS
An auto show can create excitement for three days.
Industrial transformation takes years. The real test of PAPS 2026 will therefore come after the exhibition closes. Will local vendors invest in new technologies? Will OEMs deepen localization? Will new entrants create sustainable manufacturing footprints? Will Pakistan develop export-oriented supplier capabilities? Will EV and hybrid infrastructure grow alongside vehicle sales? Will customers receive dependable after-sales support? Will policy remain consistent long enough for investors to make long-term commitments? These questions matter more than the number of vehicles displayed.
My Takeaway After Three Decades in the Industry
Having spent more than 30 years working across sales, marketing, dealer development, commercial planning, procurement and automotive operations, I came away from PAPS 2026 with a sense that Pakistan’s automotive industry is entering a newcompetitive cycle. The old industry was largely defined by a few established manufacturers, conventional powertrains and progressively increasing localization. The emerging industry will be defined by multiple technologies, new global players, faster product cycles, stronger consumer expectations, digitalization, electrification and much tougher competition.
That transition will not be easy. But it can be enormously positive for Pakistan if we approach it as an industrial opportunity rather than simply a vehicle-import or vehicle-sales opportunity. We have an established automotive ecosystem, experienced human capital, a significant vendor base, manufacturing experience and a large domestic market. And, importantly, we now have increasing exposure to global automotive technology. The next step is to connect these strengths.
The Real Opportunity
PAPS 2026 did not tell us exactly what Pakistan’s automotive industry will look like five years from now. But it gave us some strong clues. The industry is becoming more competitive. The product portfolio is becoming more technologically sophisticated. Electrification is moving from discussion towards manufacturing. Localization is moving towards a new phase. Consumers are demanding more. And global automotive companies are increasingly looking at Pakistan not merely as a market for vehicles, but potentially as
The most positive message from PAPS 2026: Pakistan’sautomotivefutureshouldnotbe aboutprotectingwhatwehave.Itshouldbeaboutbuildingwhatweneednext.
A globally competitive automotive industry will require more than assembling vehicles in Pakistan. It will require developing Pakistani suppliers, transferring technology, investing in people, improving quality, achieving cost competitiveness, embracing new-energy technologies and ultimately exporting vehicles and components to the world.
That is the real opportunity. And perhaps that is the real meaning of “IndustrialPakistan.”
The growth of Chinese automotive brands in Pakistan has been significant, driven by competitive pricing, modern design, advanced technology and an increasingly attractive product portfolio.
However, the next challenge for Chinese automotive brands is no longer simply selling more vehicles. The real opportunity is to build long-term customer trust, loyalty and confidence throughout the entire ownership journey.
At the center of this challenge is After-Sales Service.
After-Sales: The Foundation of Long-Term Customer Confidence
As the population of Chinese vehicles on Pakistani roads continues to grow, customers will increasingly judge brands not only by the vehicle they purchase, but by the quality and reliability of the support they receive after the sale.
Spare-parts availability, competitive pricing, service quality, technical support and response time will become critical differentiators.
Manufacturers and dealers therefore need to establish robust after-sales capabilities focused on:
– High spare-parts availability and supply fill rates – Competitive spare-parts pricing and an attractive total cost of ownership – Short, predictable and reliable shipping lead times – Accurate demand forecasting – Efficient ordering and replenishment processes – Strong technical support and service capabilities – Effective customer communication and issue resolution
After-sales performance must become an integral part of the brand proposition rather than being treated simply as a dealer operational responsibility.
Spare Parts Availability: A Joint Responsibility
Parts availability is not merely a matter of maintaining sufficient inventory at dealerships.
It is the result of an integrated ecosystem involving the vehicle manufacturer, local distributor, dealer network, logistics providers, information systems and operational processes.
A breakdown in any one of these areas can ultimately affect the customer.
For example, a part may be physically available at the manufacturer but unavailable to the customer because of delays in ordering, documentation, logistics, customs clearance, system integration or dealer processes.
This makes supply-chain integration critical to delivering a consistent customer experience.
Building a Professional After-Sales Infrastructure
To support sustainable growth in Pakistan, Chinese automotive manufacturers should establish professional and scalable after-sales infrastructure covering the complete parts and service value chain.
Key capabilities should include:
1. Accurate Electronic Parts Catalogues Professional electronic parts catalogues should provide accurate part numbers, VIN/application information and clear identification of applicable vehicle variants.
2. Efficient Dealer Parts Ordering Systems Dealers should have simple, reliable and transparent systems for placing, tracking and managing parts orders.
3. Clear and Reliable Shipping Lead Times Dealers and customers should have realistic delivery expectations supported by reliable logistics processes.
4. Strong Supply Fill Rates and Order Fulfilment The objective should be to maximize first-time fulfilment and minimize customer waiting time.
5. Effective Urgent and Back-Order Processes Clearly defined procedures should exist for critical, urgent and back-ordered parts, with appropriate escalation mechanisms.
6. Manufacturer–Dealer System Integration Integration between the manufacturer’s systems and the dealer’s Dealer Management System (DMS) can improve visibility, forecasting, ordering, inventory management and customer communication.
The Customer Sees Only One Brand
From the customer’s perspective, responsibility is straightforward.
If a required part is unavailable or a repair is delayed, the customer generally does not distinguish whether the problem originated with the dealer, manufacturer, logistics provider, ordering system or supply chain.
The customer simply experiences it as a brand problem.
This is why after-sales performance should be managed as a joint manufacturer–dealer responsibility, supported by clearly defined processes, ownership and measurable performance indicators.
Important KPIs should include:
– Parts availability – Supply fill rate – Order accuracy – Order fulfilment – Delivery lead time – Back-order ageing – Emergency parts response time – Customer repair turnaround time – Warranty claim turnaround time – Customer satisfaction
What gets measured, reviewed and improved consistently is far more likely to become a sustainable competitive capability.
The Benchmark Already Exists in Pakistan
Pakistani customers have experienced established after-sales standards from Japanese and Korean automotive brands. As a result, customer expectations have been shaped not only by vehicle quality, but also by parts availability, service quality, technical expertise, pricing, reliability and customer care.
Chinese automotive brands therefore enter the Pakistani market with an important opportunity—and a clear benchmark.
They have already demonstrated their ability to compete strongly in areas such as vehicle design, technology, features and pricing.
The next step is to demonstrate the same level of excellence in after-sales operations, spare-parts availability and supply-chain reliability.
From Selling Vehicles to Managing the Ownership Journey
The automotive business is not completed when a vehicle is delivered to the customer.
In many respects, that is where the customer relationship truly begins.
Every service visit, spare-parts requirement, warranty claim and technical interaction becomes another opportunity for the brand to either strengthen or weaken customer confidence.
Chinese automotive brands that develop a strong after-sales ecosystem from the beginning can convert vehicle sales into long-term customer relationships.
This requires close alignment between the manufacturer and dealer network, investment in systems and processes, strong parts planning, professional technical support and a customer-centric service culture.
The Strategic Imperative
The future success of Chinese automotive brands in Pakistan will depend not only on how many vehicles they sell, but on how effectively they support those vehicles throughout their ownership lifecycle.
Selling the car is only the beginning. Supporting the customer throughout the ownership journey is what builds the brand.
The next competitive advantage in Pakistan’s automotive industry may therefore not be found only in the showroom.
It may be found in the parts warehouse, the supply chain, the workshop, the technical support center and every customer interaction after the sale.
Dear Readers, For the current month’s theme for Automark magazine is PAPS 2026 Auto Show. Pakistan’s Automotive Potential and Future Direction has been chosen as the main theme of the month because a Pakistan Auto Show is about more than just cars, parts, and technology. This event offers us a chance to examine the entire automotive industry and see where Pakistan stands in terms of its position, what has been achieved throughout the years, the existing challenges, and the upcoming opportunities. The future cannot be judged merely on the grounds of the volume of production and the number of companies in attendance at a show. The future of an industry depends upon the creation of local value, technology advancement, competitiveness of the products, supply chain reliability, and success in international market penetration.
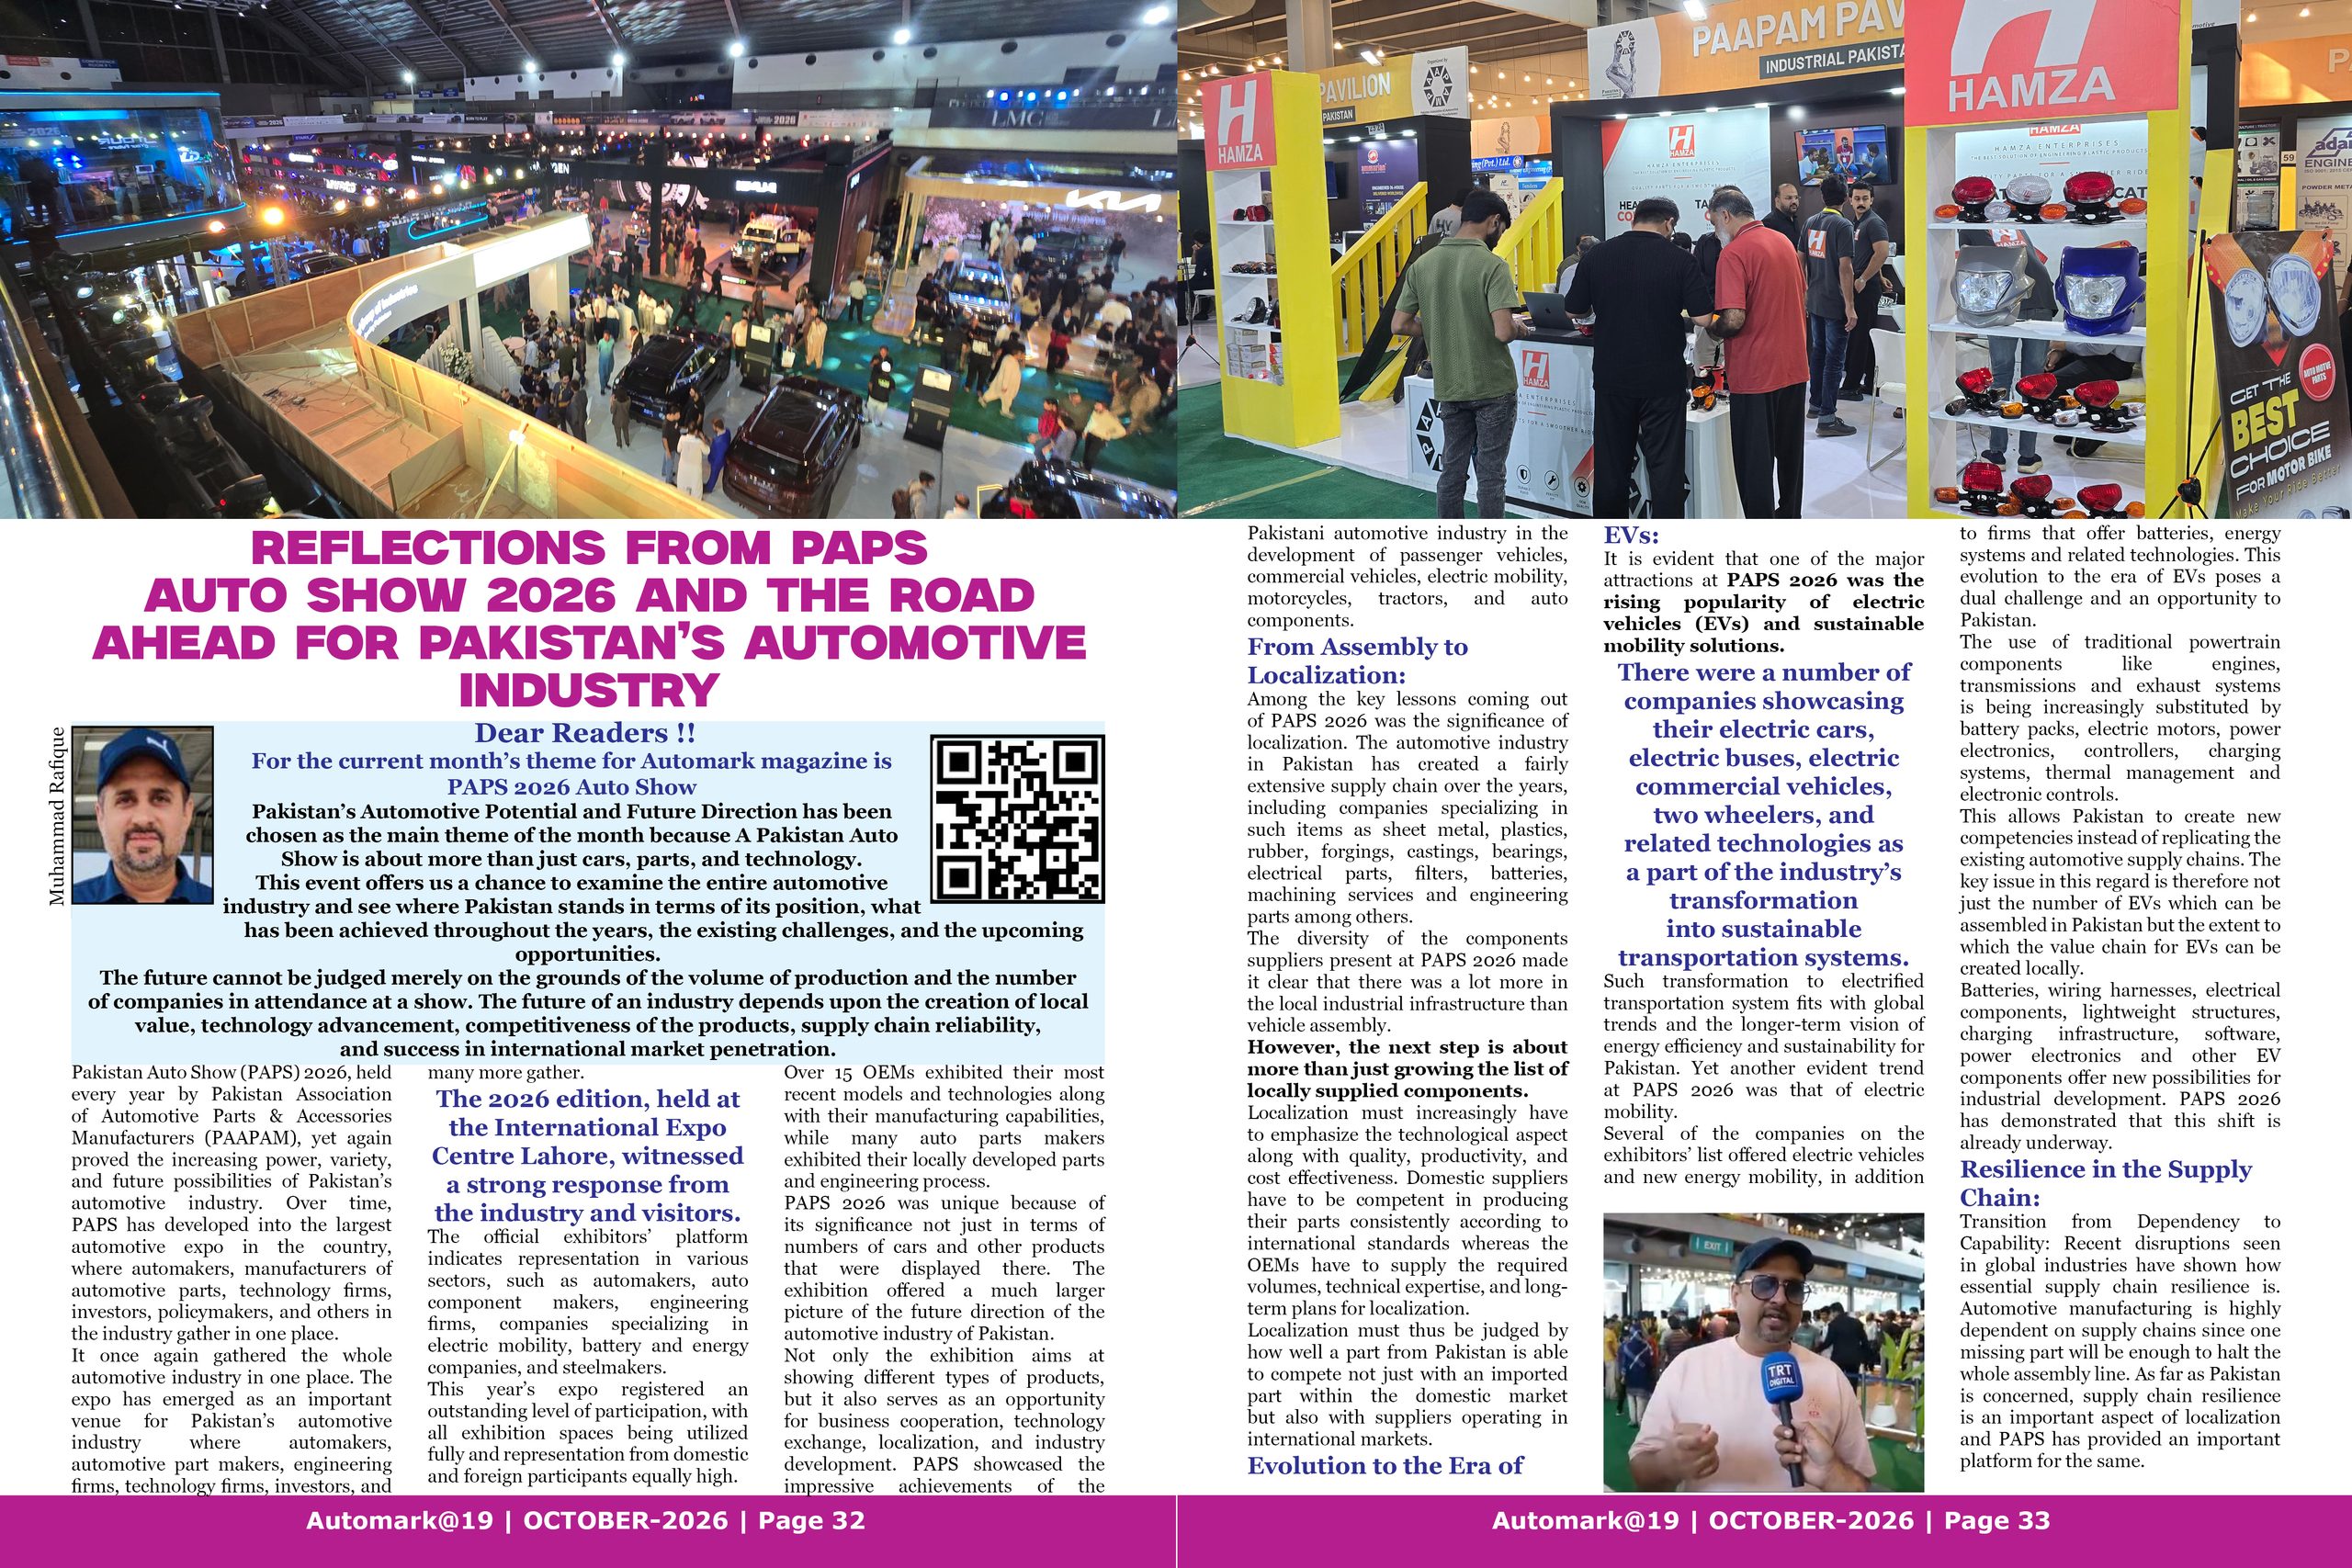
Pakistan Auto Show (PAPS) 2026, held every year by Pakistan Association of Automotive Parts & Accessories Manufacturers (PAAPAM), yet again proved the increasing power, variety, and future possibilities of Pakistan’s automotive industry. Over time, PAPS has developed into the largest automotive expo in the country, where automakers, manufacturers of automotive parts, technology firms, investors, policymakers, and others in the industry gather in one place. It once again gathered the whole automotive industry in one place. The expo has emerged as an important venue for Pakistan’s automotive industry where automakers, automotive part makers, engineering firms, technology firms, investors, and many more gather.
The 2026 edition, held at the International Expo Centre Lahore, witnessed a strong response from the industry and visitors. The official exhibitors’ platform indicates representation in various sectors, such as automakers, auto component makers, engineering firms, companies specializing in electric mobility, battery and energy companies, and steelmakers. This year’s expo registered an outstanding level of participation, with all exhibition spaces being utilized fully and representation from domestic and foreign participants equally high. Over 15 OEMs exhibited their most recent models and technologies along with their manufacturing capabilities, while many auto parts makers exhibited their locally developed parts and engineering process.
PAPS 2026 was unique because of its significance not just in terms of numbers of cars and other products that were displayed there. The exhibition offered a much larger picture of the future direction of the automotive industry of Pakistan. Not only the exhibition aims at showing different types of products, but it also serves as an opportunity for business cooperation, technology exchange, localization, and industry development. PAPS showcased the impressive achievements of the Pakistani automotive industry in the development of passenger vehicles, commercial vehicles, electric mobility, motorcycles, tractors, and auto components.
From Assembly to Localization: Among the key lessons coming out of PAPS 2026 was the significance of localization. The automotive industry in Pakistan has created a fairly extensive supply chain over the years, including companies specializing in such items as sheet metal, plastics, rubber, forgings, castings, bearings, electrical parts, filters, batteries, machining services and engineering parts among others. The diversity of the components suppliers present at PAPS 2026 made it clear that there was a lot more in the local industrial infrastructure than vehicle assembly. However, the next step is about more than just growing the list of locally supplied components. Localization must increasingly have to emphasize the technological aspect along with quality, productivity, and cost effectiveness. Domestic suppliers have to be competent in producing their parts consistently according to international standards whereas the OEMs have to supply the required volumes, technical expertise, and long-term plans for localization. Localization must thus be judged by how well a part from Pakistan is able to compete not just with an imported part within the domestic market but also with suppliers operating in international markets.
Evolution to the Era of EVs: It is evident that one of the major attractions at PAPS 2026 was the rising popularity of electric vehicles (EVs) and sustainable mobility solutions. There were a number of companies showcasing their electric cars, electric buses, electric commercial vehicles, two wheelers, and related technologies as a part of the industry’s transformation into sustainable transportation systems. Such transformation to electrified transportation system fits with global trends and the longer-term vision of energy efficiency and sustainability for Pakistan. Yet another evident trend at PAPS 2026 was that of electric mobility. Several of the companies on the exhibitors’ list offered electric vehicles and new energy mobility, in addition to firms that offer batteries, energy systems and related technologies. This evolution to the era of EVs poses a dual challenge and an opportunity to Pakistan. The use of traditional powertrain components like engines, transmissions and exhaust systems is being increasingly substituted by battery packs, electric motors, power electronics, controllers, charging systems, thermal management and electronic controls. This allows Pakistan to create new competencies instead of replicating the existing automotive supply chains. The key issue in this regard is therefore not just the number of EVs which can be assembled in Pakistan but the extent to which the value chain for EVs can be created locally. Batteries, wiring harnesses, electrical components, lightweight structures, charging infrastructure, software, power electronics and other EV components offer new possibilities for industrial development. PAPS 2026 has demonstrated that this shift is already underway.
Resilience in the Supply Chain: Transition from Dependency to Capability: Recent disruptions seen in global industries have shown how essential supply chain resilience is. Automotive manufacturing is highly dependent on supply chains since one missing part will be enough to halt the whole assembly line. As far as Pakistan is concerned, supply chain resilience is an important aspect of localization and PAPS has provided an important platform for the same.
From Domestic Market to Export Market: One of the major opportunities that could be seen with the advent of PAPS 2026 is the shift of industry from being domestic market-oriented to being export-oriented in nature. Pakistan has many components of success like automotive manufacturing capability, vendor base, engineering resources, and infrastructure.
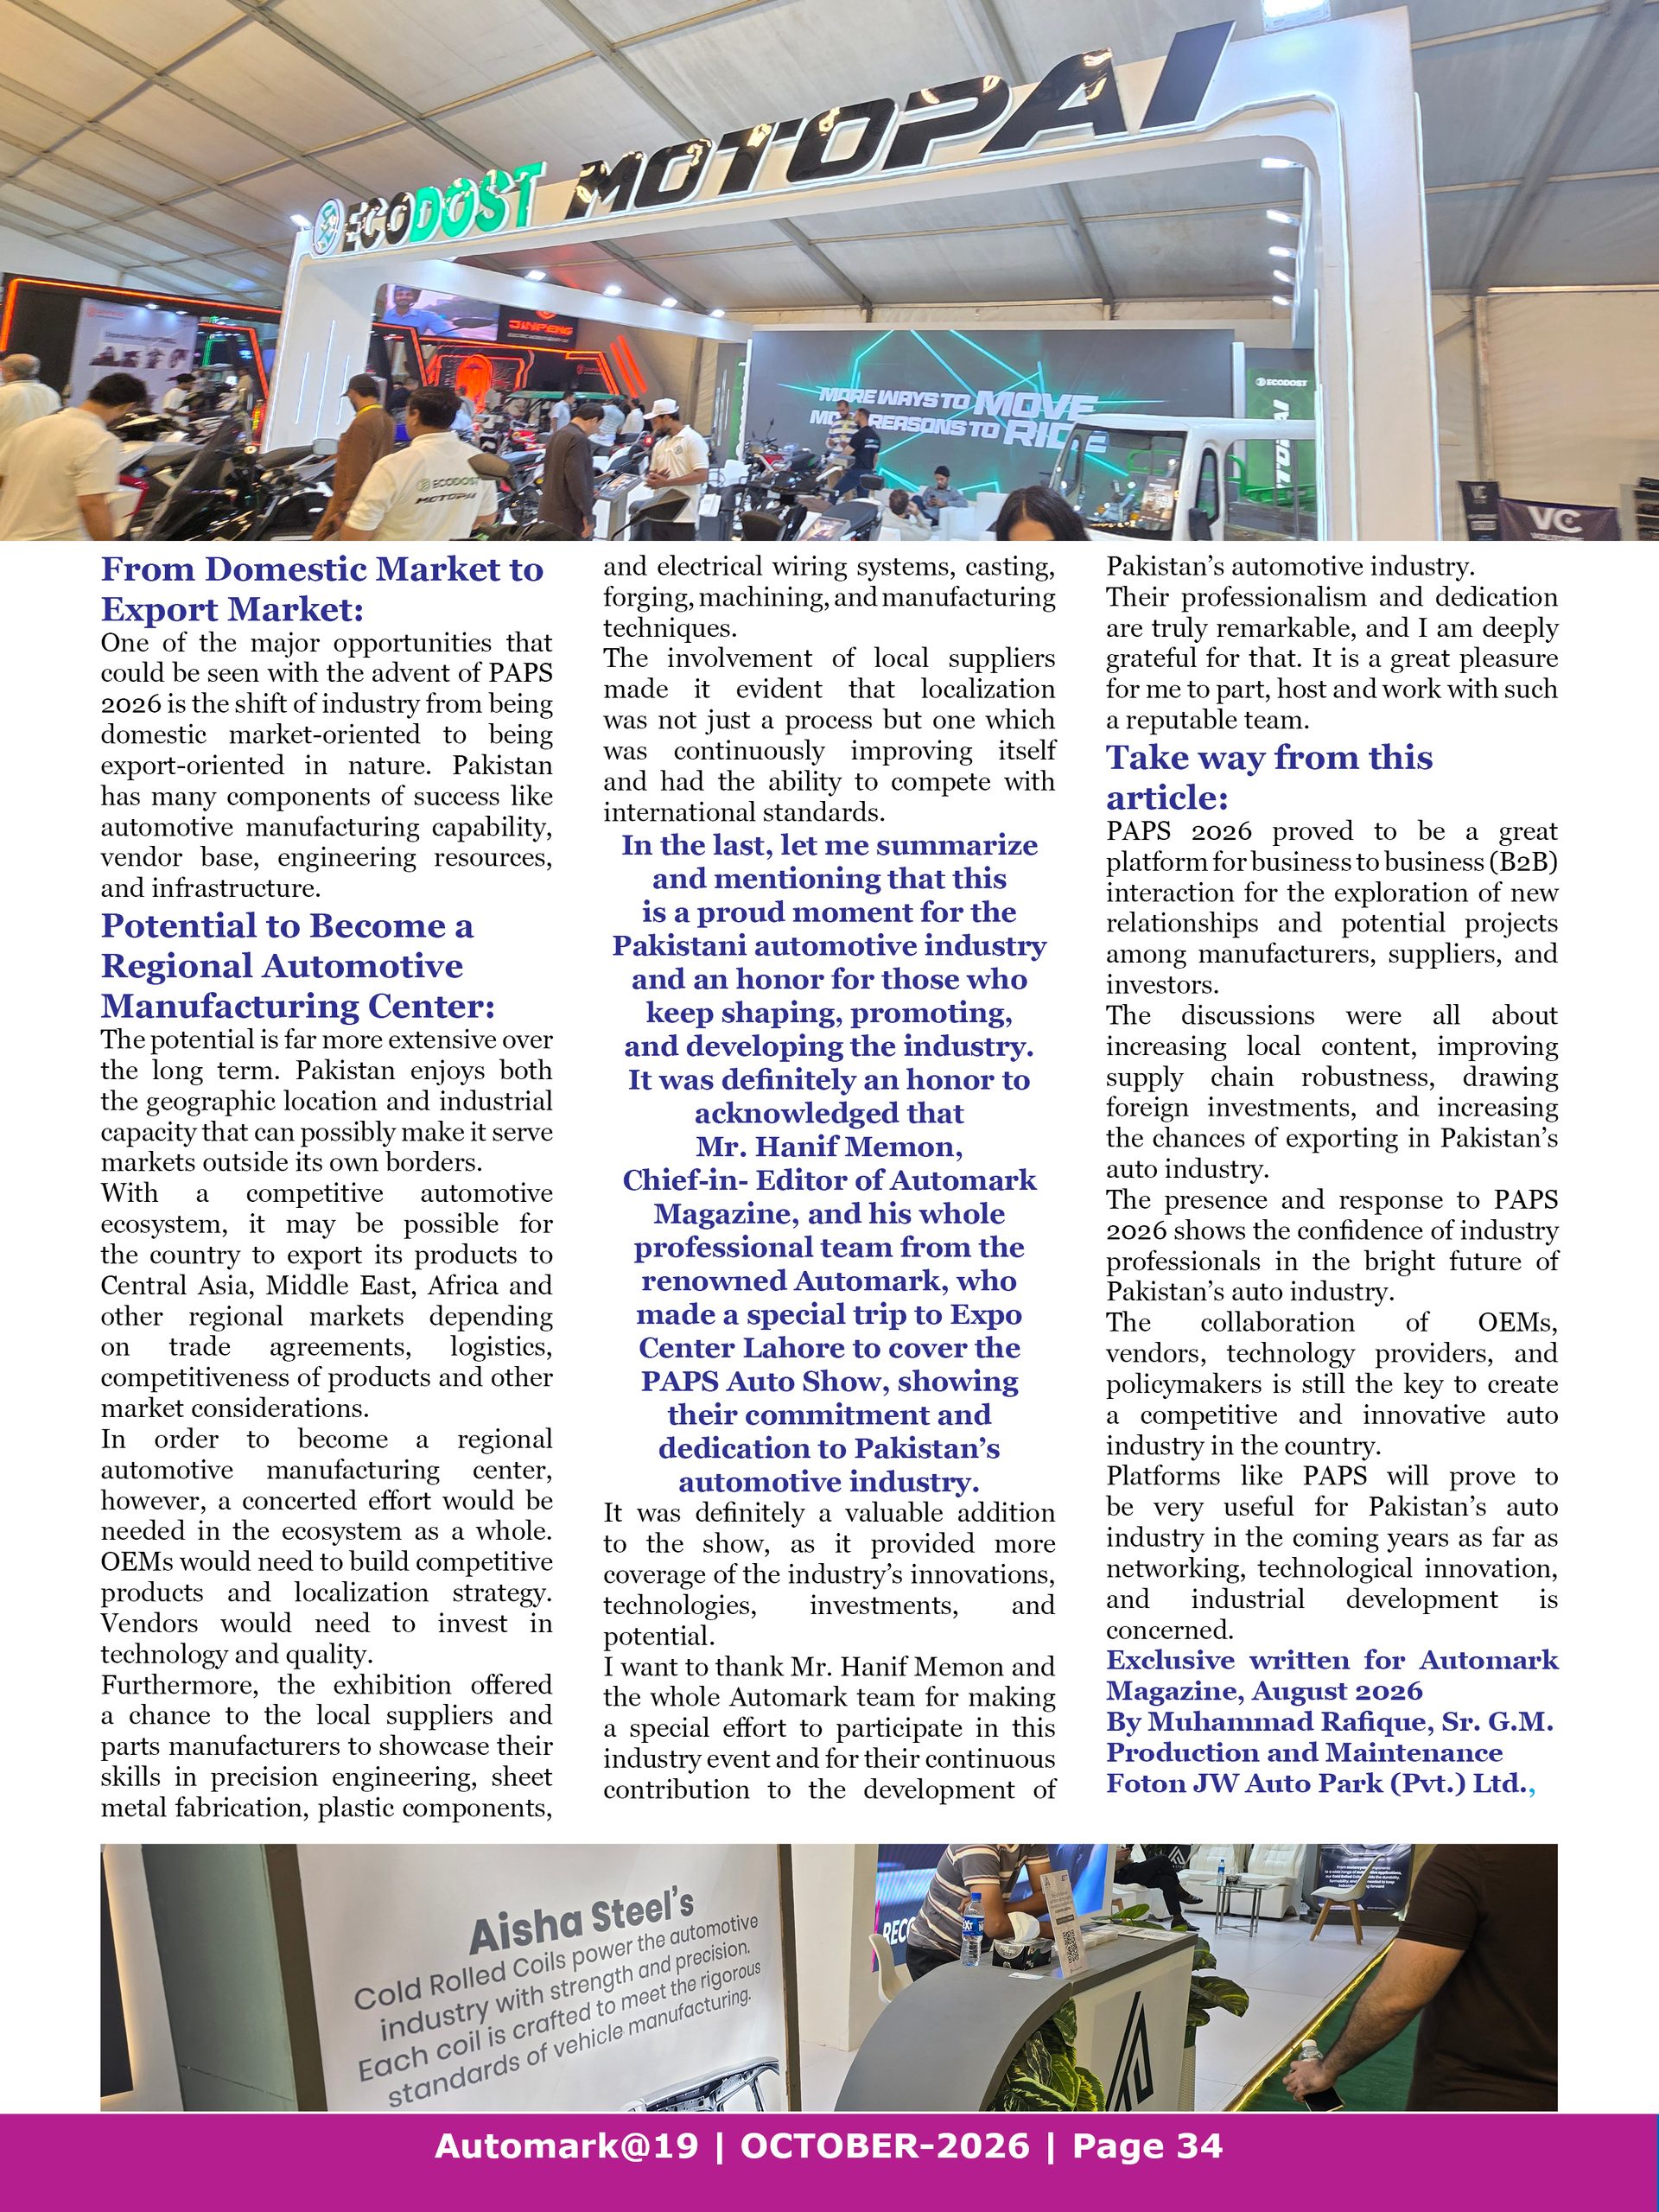
Potential to Become a Regional Automotive Manufacturing Center: The potential is far more extensive over the long term. Pakistan enjoys both the geographic location and industrial capacity that can possibly make it serve markets outside its own borders. With a competitive automotive ecosystem, it may be possible for the country to export its products to Central Asia, Middle East, Africa and other regional markets depending on trade agreements, logistics, competitiveness of products and other market considerations. In order to become a regional automotive manufacturing center, however, a concerted effort would be needed in the ecosystem as a whole. OEMs would need to build competitive products and localization strategy. Vendors would need to invest in technology and quality. Furthermore, the exhibition offered a chance to the local suppliers and parts manufacturers to showcase their skills in precision engineering, sheet metal fabrication, plastic components, and electrical wiring systems, casting, forging, machining, and manufacturing techniques. The involvement of local suppliers made it evident that localization was not just a process but one which was continuously improving itself and had the ability to compete with international standards.
In the last, let me summarize and mentioning that this is a proud moment for the Pakistani automotive industry and an honor for those who keep shaping, promoting, and developing the industry. It was definitely an honor to acknowledged that Mr. Hanif Memon, Chief Editor of Automark Magazine, and his whole professional team from the renowned Automark, who made a special trip to Lahore to cover the PAPS Auto Show, showing their commitment and dedication to Pakistan’s automotive industry. It was definitely a valuable addition to the show, as it provided more coverage of the industry’s innovations, technologies, investments, and potential. I want to thank Mr. Hanif Memon and the whole Automark team for making a special effort to participate in this industry event and for their continuous contribution to the development of Pakistan’s automotive industry. Their professionalism and dedication are truly remarkable, and I am deeply grateful for that. It is a great pleasure for me to part, host and work with such a reputable team.
Take way from this article:
PAPS 2026 proved to be a great platform for business to business (B2B) interaction for the exploration of new relationships and potential projects among manufacturers, suppliers, and investors. The discussions were all about increasing local content, improving supply chain robustness, drawing foreign investments, and increasing the chances of exporting in Pakistan’s auto industry. The presence and response to PAPS 2026 shows the confidence of industry professionals in the bright future of Pakistan’s auto industry. The collaboration of OEMs, vendors, technology providers, and policymakers is still the key to create a competitive and innovative auto industry in the country. Platforms like PAPS will prove to be very useful for Pakistan’s auto industry in the coming years as far as networking, technological innovation, and industrial development is concerned.
This exclusive article has been published in Automark’s October-2026 printed and digital edition. Written by @muhammad-rafique
This year a symposium was held at PAPS Show 2026 in Lahore organized by Iftikhar Ahmed Former Chairman PAAPAM. The Symposium brought together government representative, economists, technology experts, OEM representatives and engineering SMEs to discuss the future direction of Pakistan automotive industry.
Pakistan’s automotive industry is entering a new phase – From ICE vehicles toward hybrids, plug-in hybrids and new-energy vehicles is presenting an opportunity but also a strategic choice in Pakistan.
This question shaped the discussion at the PAAPAM symposium, “Future of Wheels in Pakistan: Electric Mobility, Competitiveness, Localization & Electric Mobility,”
The discussion covered a broad range of issues from tariffs and EVs to technology, vendor development, exports, energy costs and policy stability. Together, the presentations highlighted a central requirement: Pakistan must use the automotive transition to strengthen its manufacturing capabilities rather than simply expand assembly.
Rana Ihsaan Afzal Khan: Tariffs Are an Instrument, Competitiveness Is the Goal
Rana Ihsaan Afzal Khan, Coordinator to the Prime Minister, emphasized the importance of the automotive ecosystem beyond vehicle assembly.
The industry supports a much wider network involving steel, plastics, rubber, software, logistics, designing, tooling and engineering services. The figures discussed at the symposium indicated around 2,200 component manufacturers and approximately 3,500 engineering SMEs connected with this broader industrial base.
He stressed that tariffs should not be viewed as the final objective of industrial policy.
“Tariff is an instrument; the destination is competitiveness.”
This becomes particularly important as Pakistan moves toward new-energy mobility. The question is whether the country will become primarily an importer of EV components, an assembler, or a manufacturer.
The government is also considering increased production of L6 and L7 vehicles, while EV adoption could contribute to reduced oil imports and lower emissions.
But these benefits will be greater if the transition also creates domestic manufacturing capability.
Rana Ihsaan emphasized the need to identify productivity gaps, close them and continuously monitor improvements. The same discipline, he suggested, should apply to the broader concept of Made in Pakistan.
Mr. Asif Saeed Khan Lughmani, Additional Secretary, Ministry of Industries & Production, addressed the policy environment in which the industry must operate.
Pakistan is moving toward greater liberalization and must also fulfil international commitments. The challenge, therefore, is not simply whether the country should liberalize or protect domestic industry.
The more important question is:
How can liberalization lead to greater competitiveness and domestic value addition?
The transition to EVs and other new-energy technologies provides an opportunity to establish new domestic capabilities but only if policy encourages investment, technology development and local production.
Economist Mr. Ashfaq Tola focused on the importance of long-term policy stability.
He therefore emphasized the importance of sustainable, predictable policies capable of giving investors confidence.
Tola also highlighted the need to improve productivity, address energy costs and attract FDI linked to export-oriented production.
Foreign investment should contribute not only capital but also technology, production capability and access to international markets.
From the OEM perspective, Mr. Faisal highlighted the rapid transformation taking place in Pakistan’s automotive market.
The market now includes a much wider range of brands, models and technologies, including HEVs, PHEVs and new-energy vehicles.
The consumer is becoming an increasingly important driver of change. Buyers are comparing technologies, prices, features and operating costs across a much broader range of vehicles.
Battery costs were also discussed as an important factor in EV affordability. The battery component of vehicle cost has declined significantly from historical levels, improving the potential economics of electric mobility.
However, taxation and incentives remain important in determining how quickly consumers adopt new technologies.
The message from the OEM perspective was that Pakistan needs a stable policy framework that allows manufacturers and consumers to plan for the technological transition.
Mashood Khan: Pakistan Must Build the Supply Chain, Not Replace It
Representing engineering SMEs, Mashood Khan focused on supply chains, partnerships and indigenization.
Pakistan has already developed a significant base of automotive and engineering manufacturers. The challenge is to connect these companies more effectively with OEMs, international technology providers and global customers.
His central proposition was that localization, technology and partnerships must develop together.
Pakistan’s domestic automotive supply chain has faced growing competition from imported components, including CBU, CKD and SKD-related imports. If imports increase without corresponding localization, domestic manufacturing capability can weaken.
Mashood Khan posed the fundamental question:
“Are we aiming at industrialization or an assembly-based economy?”
Industry figures discussed at the symposium indicated existing localization levels of approximately:
• Cars – 65% • Tractors – 90% • Two-wheelers – 90% • Trucks and buses – 40% • NEVs – currently almost zero
Against this background, he questioned whether future targets for some categories should be below levels, already achieved by local manufacturers.
The objective, he argued, should be to build on existing industrial capability and move toward higher localization and stronger exports.
The Global Aftermarket Opportunity
Mashood Khan also highlighted the international automotive aftermarket as a major opportunity for Pakistani manufacturers.
The global aftermarket was discussed as a market of approximately USD 2.4 trillion, while Pakistan’s current share remains very small.
This creates considerable room for growth, particularly in Europe, the United States and Africa.
Pakistan should not focus only on large vehicle components. Smaller accessories and niche products can also provide practical entry points for SMEs.
However, international buyers demand quality, reliability, certification and consistent delivery.
For this reason, Pakistan needs stronger testing, validation and certification infrastructure.
The objective should be to create manufacturers capable of meeting international standards and developing long-term relationships with global distributors.
As Mashood Khan put it, Pakistan needs more “Export Entrepreneurs” companies that build their business around international markets rather than treating exports as an occasional activity.
Two areas discussed as examples of potential export growth were aluminium automotive parts and forged components.
The combined global aftermarket opportunity for these areas was cited at approximately USD 180 billion.
Pakistan does not need to capture the entire market. Even a small share could generate meaningful export revenues if domestic manufacturers have access to appropriate technology, raw materials, financing, testing and international buyers.
The challenge is to create the ecosystem that allows SMEs to make the required investments.
A Five-Point Roadmap for Export Growth
Mashood Khan proposed five practical areas for government and industry cooperation:
1. SME Engineering Clusters
Develop specialized automotive and SME engineering clusters in Karachi and Lahore, providing shared infrastructure and access to technology, testing, training and supply-chain services.
2. Technology Upgradation
Facilitate affordable long-term financing for modern machinery, automation and production technology, with financing structures suitable for SMEs.
3. Technical Partnerships and Joint Ventures
Government institutions can help Pakistani manufacturers identify international technology partners and establish technical agreements and joint ventures.
4. Domestic Raw Materials
Domestic raw materials are most essential for exporter to compete globally to enhance export from Pakistan. Initially Import data can be used to identify strategically important engineering materials that Pakistan imports in significant quantities. International suppliers can then be encouraged to establish manufacturing partnerships with Pakistani companies.
5. Industrial Land and Infrastructure
Once viable projects are identified, government can facilitate appropriate industrial land and infrastructure for manufacturing and joint-venture projects.
These measures would help connect technology, manufacturing capacity and international markets.
“30 Countries, 30 Distributors and 30 Deals”
One practical proposal was the concept of:
30 Countries – 30 Global Distributors – 30 Deals
Pakistan Auto Show can become a platform for bringing international aftermarket distributors and Pakistani manufacturers together.
TDAP, commercial counsellors and Pakistani diplomatic missions can play an important role in identifying potential buyers.
The objective should be measurable: bring serious buyers to Pakistan, connect them with manufacturers and convert business meetings into commercial relationships.
Technology expert Prof. Dr. Azam Amjad emphasized localization, job creation and technology upgrading.
Pakistan needs a stable industrial policy that allows manufacturers to improve gradually while preparing for greater international competition.
Technology transfer should therefore become an integral part of automotive development.
The EV transition creates opportunities in new areas, but Pakistan must develop the ability to absorb and use those technologies rather than remaining dependent on imported systems.
The objective should be to move progressively from technology adoption toward technology capability and eventually technology-based exports.
Aamir: Competitiveness Begins With the Industrial Environment
Auto-parts manufacturer Mr. Aamir highlighted several structural barriers facing Pakistani manufacturers.
These include:
• Lack of trust between government and the private sector;
• High electricity costs;
• Limited availability of raw materials;
• Safety and security concerns;
• Trade and FTA challenges; and
• Broader constraints on industrial competitiveness.
Conclusion
This symposium proved to be a platform where most meaningful discussions were held. The symposium gave a thought that automotive policy must look beyond vehicles assembly. It also demonstrated that Pakistan Automotive Industry future cannot be separated from the future of its engineering SMEs.
Published in Automark’s October-2026 printed and digital edition.
Dear Readers Pakistan’s automotive market is seeing an influx of new brands and models. For local distributors, however, launching a vehicle is only the beginning. The bigger challenge is building the after-sales infrastructure and customer confidence needed to sustain long-term growth.
Pakistan’s automotive market is entering a new phase
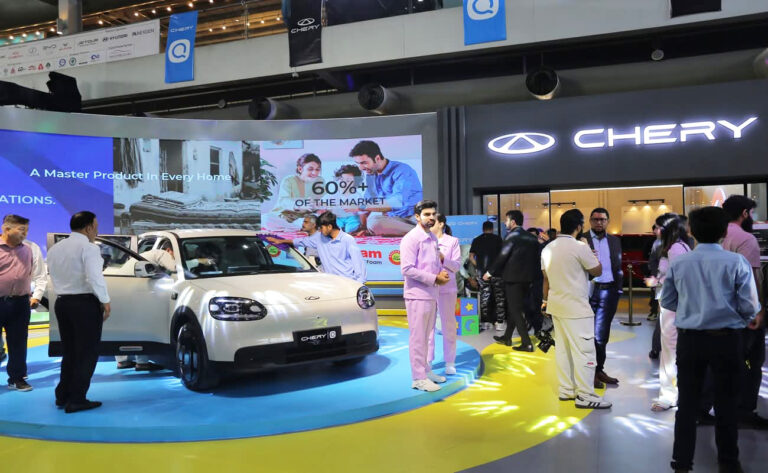
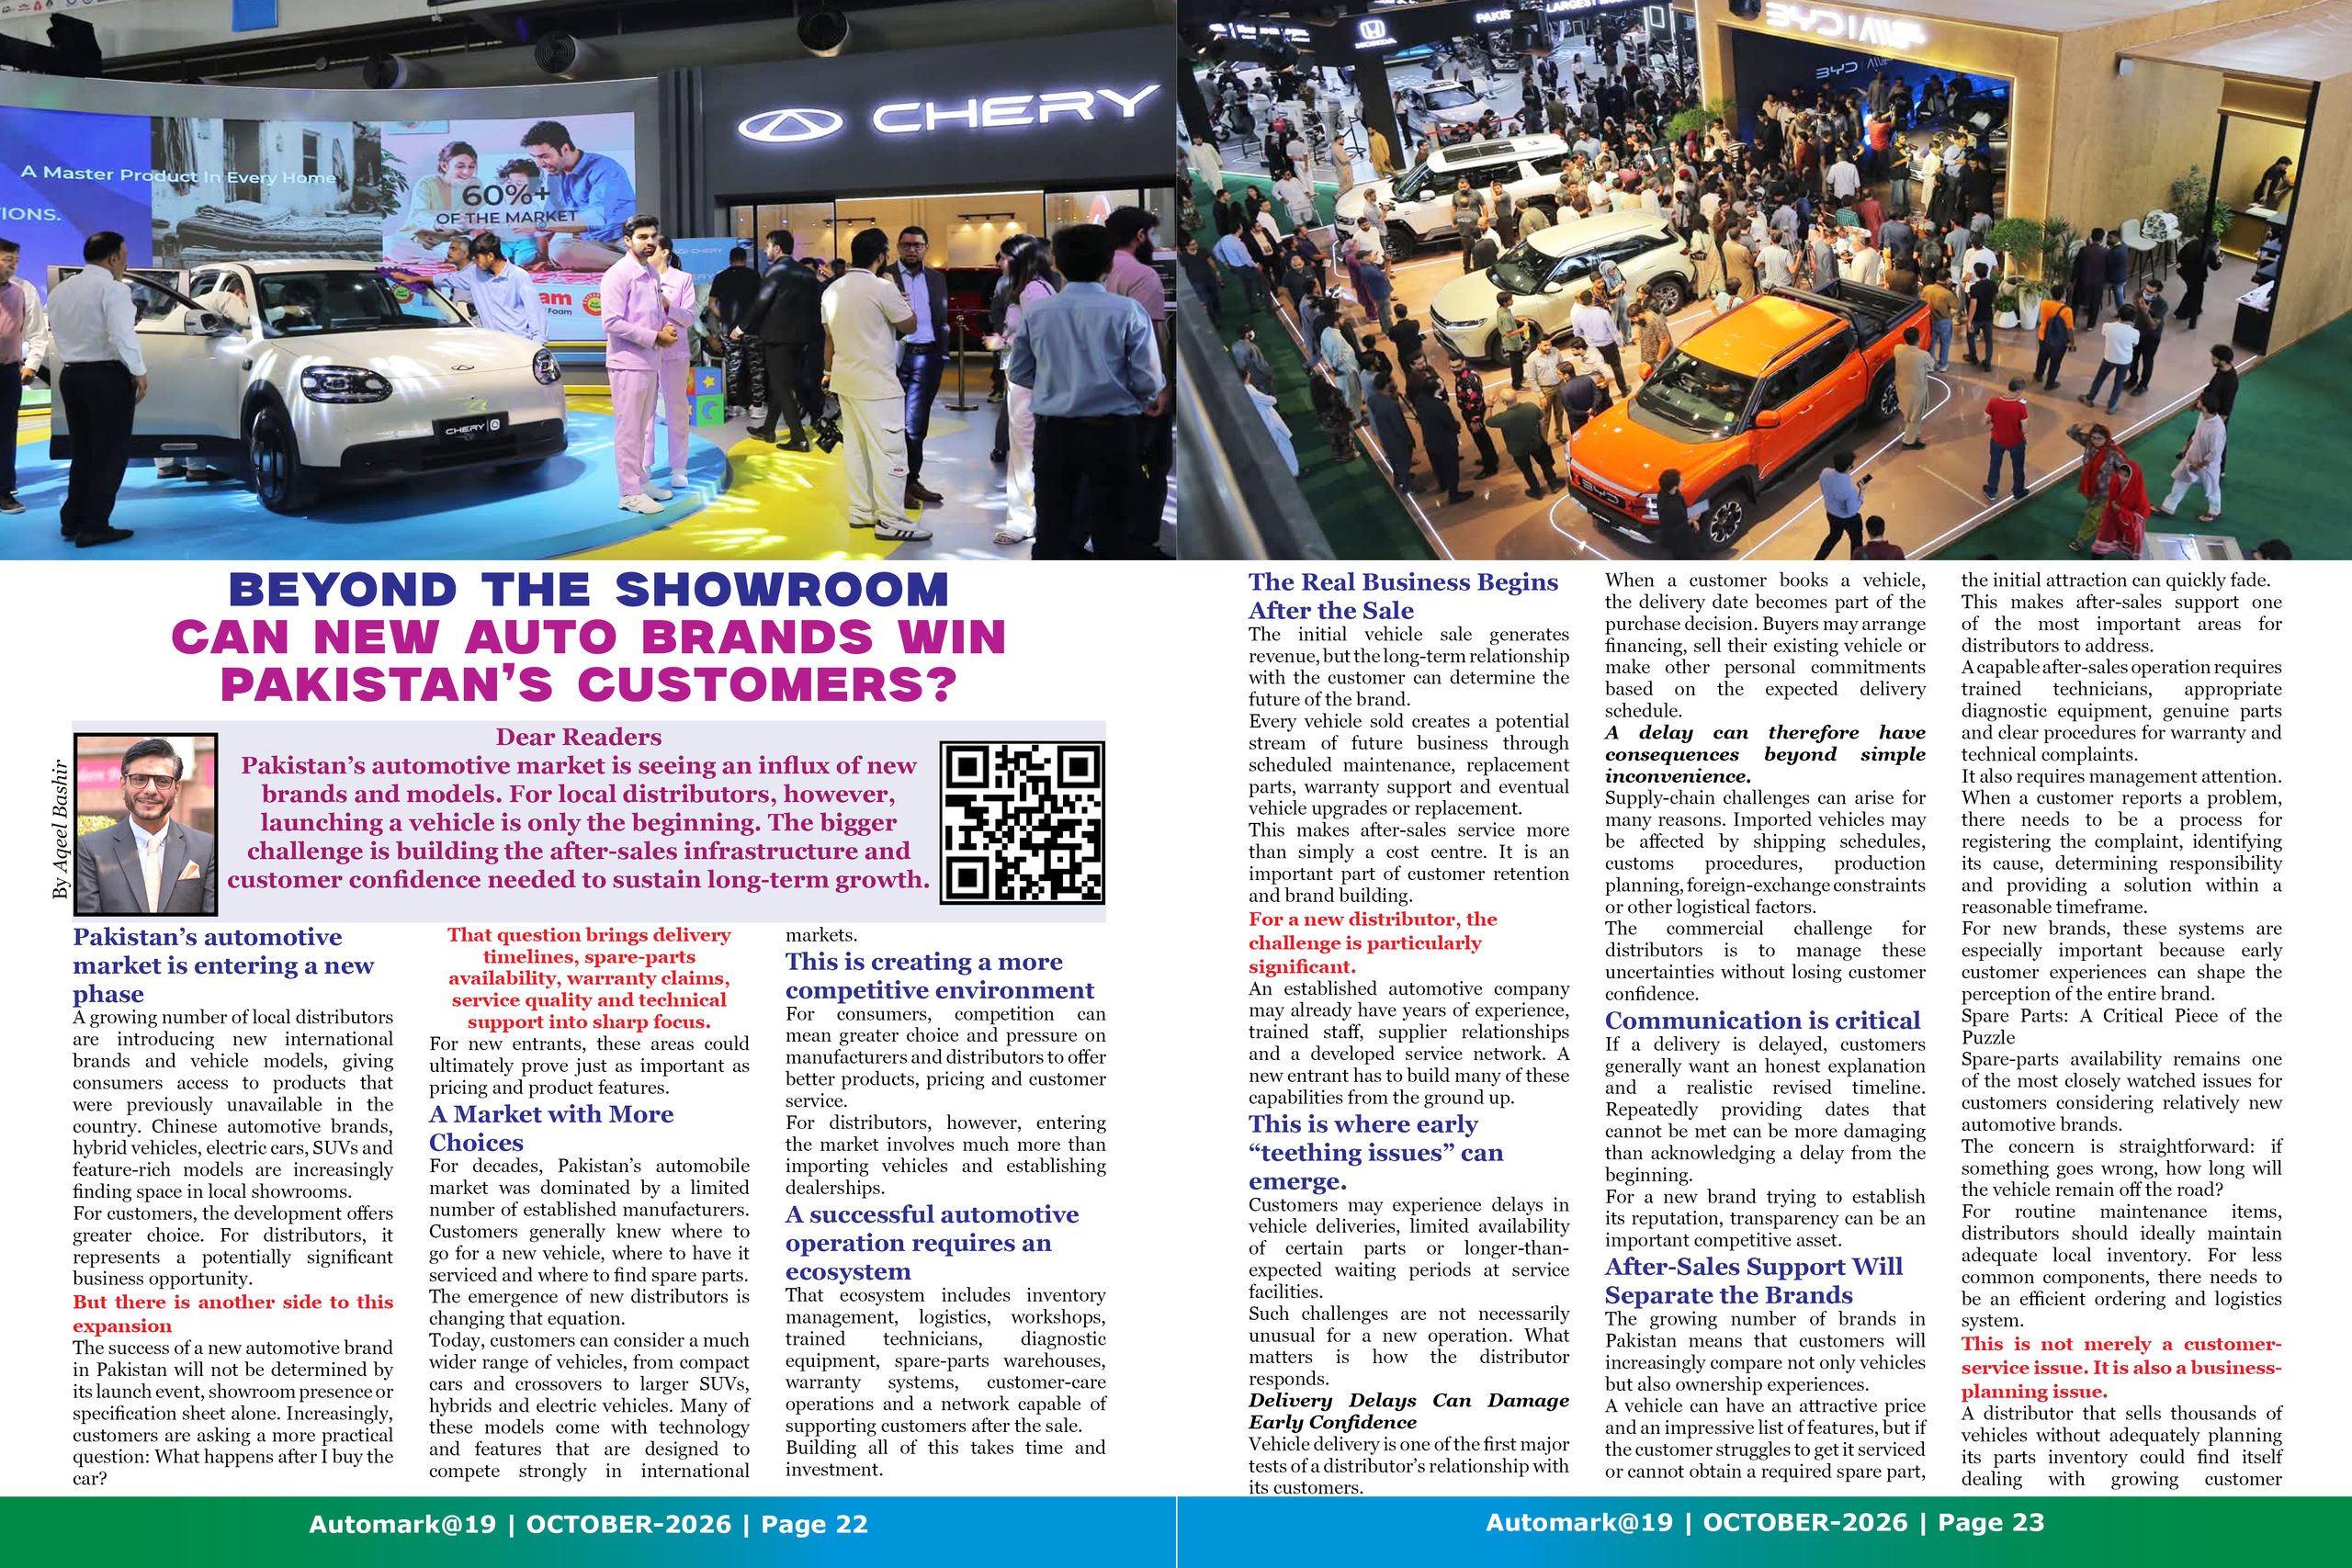
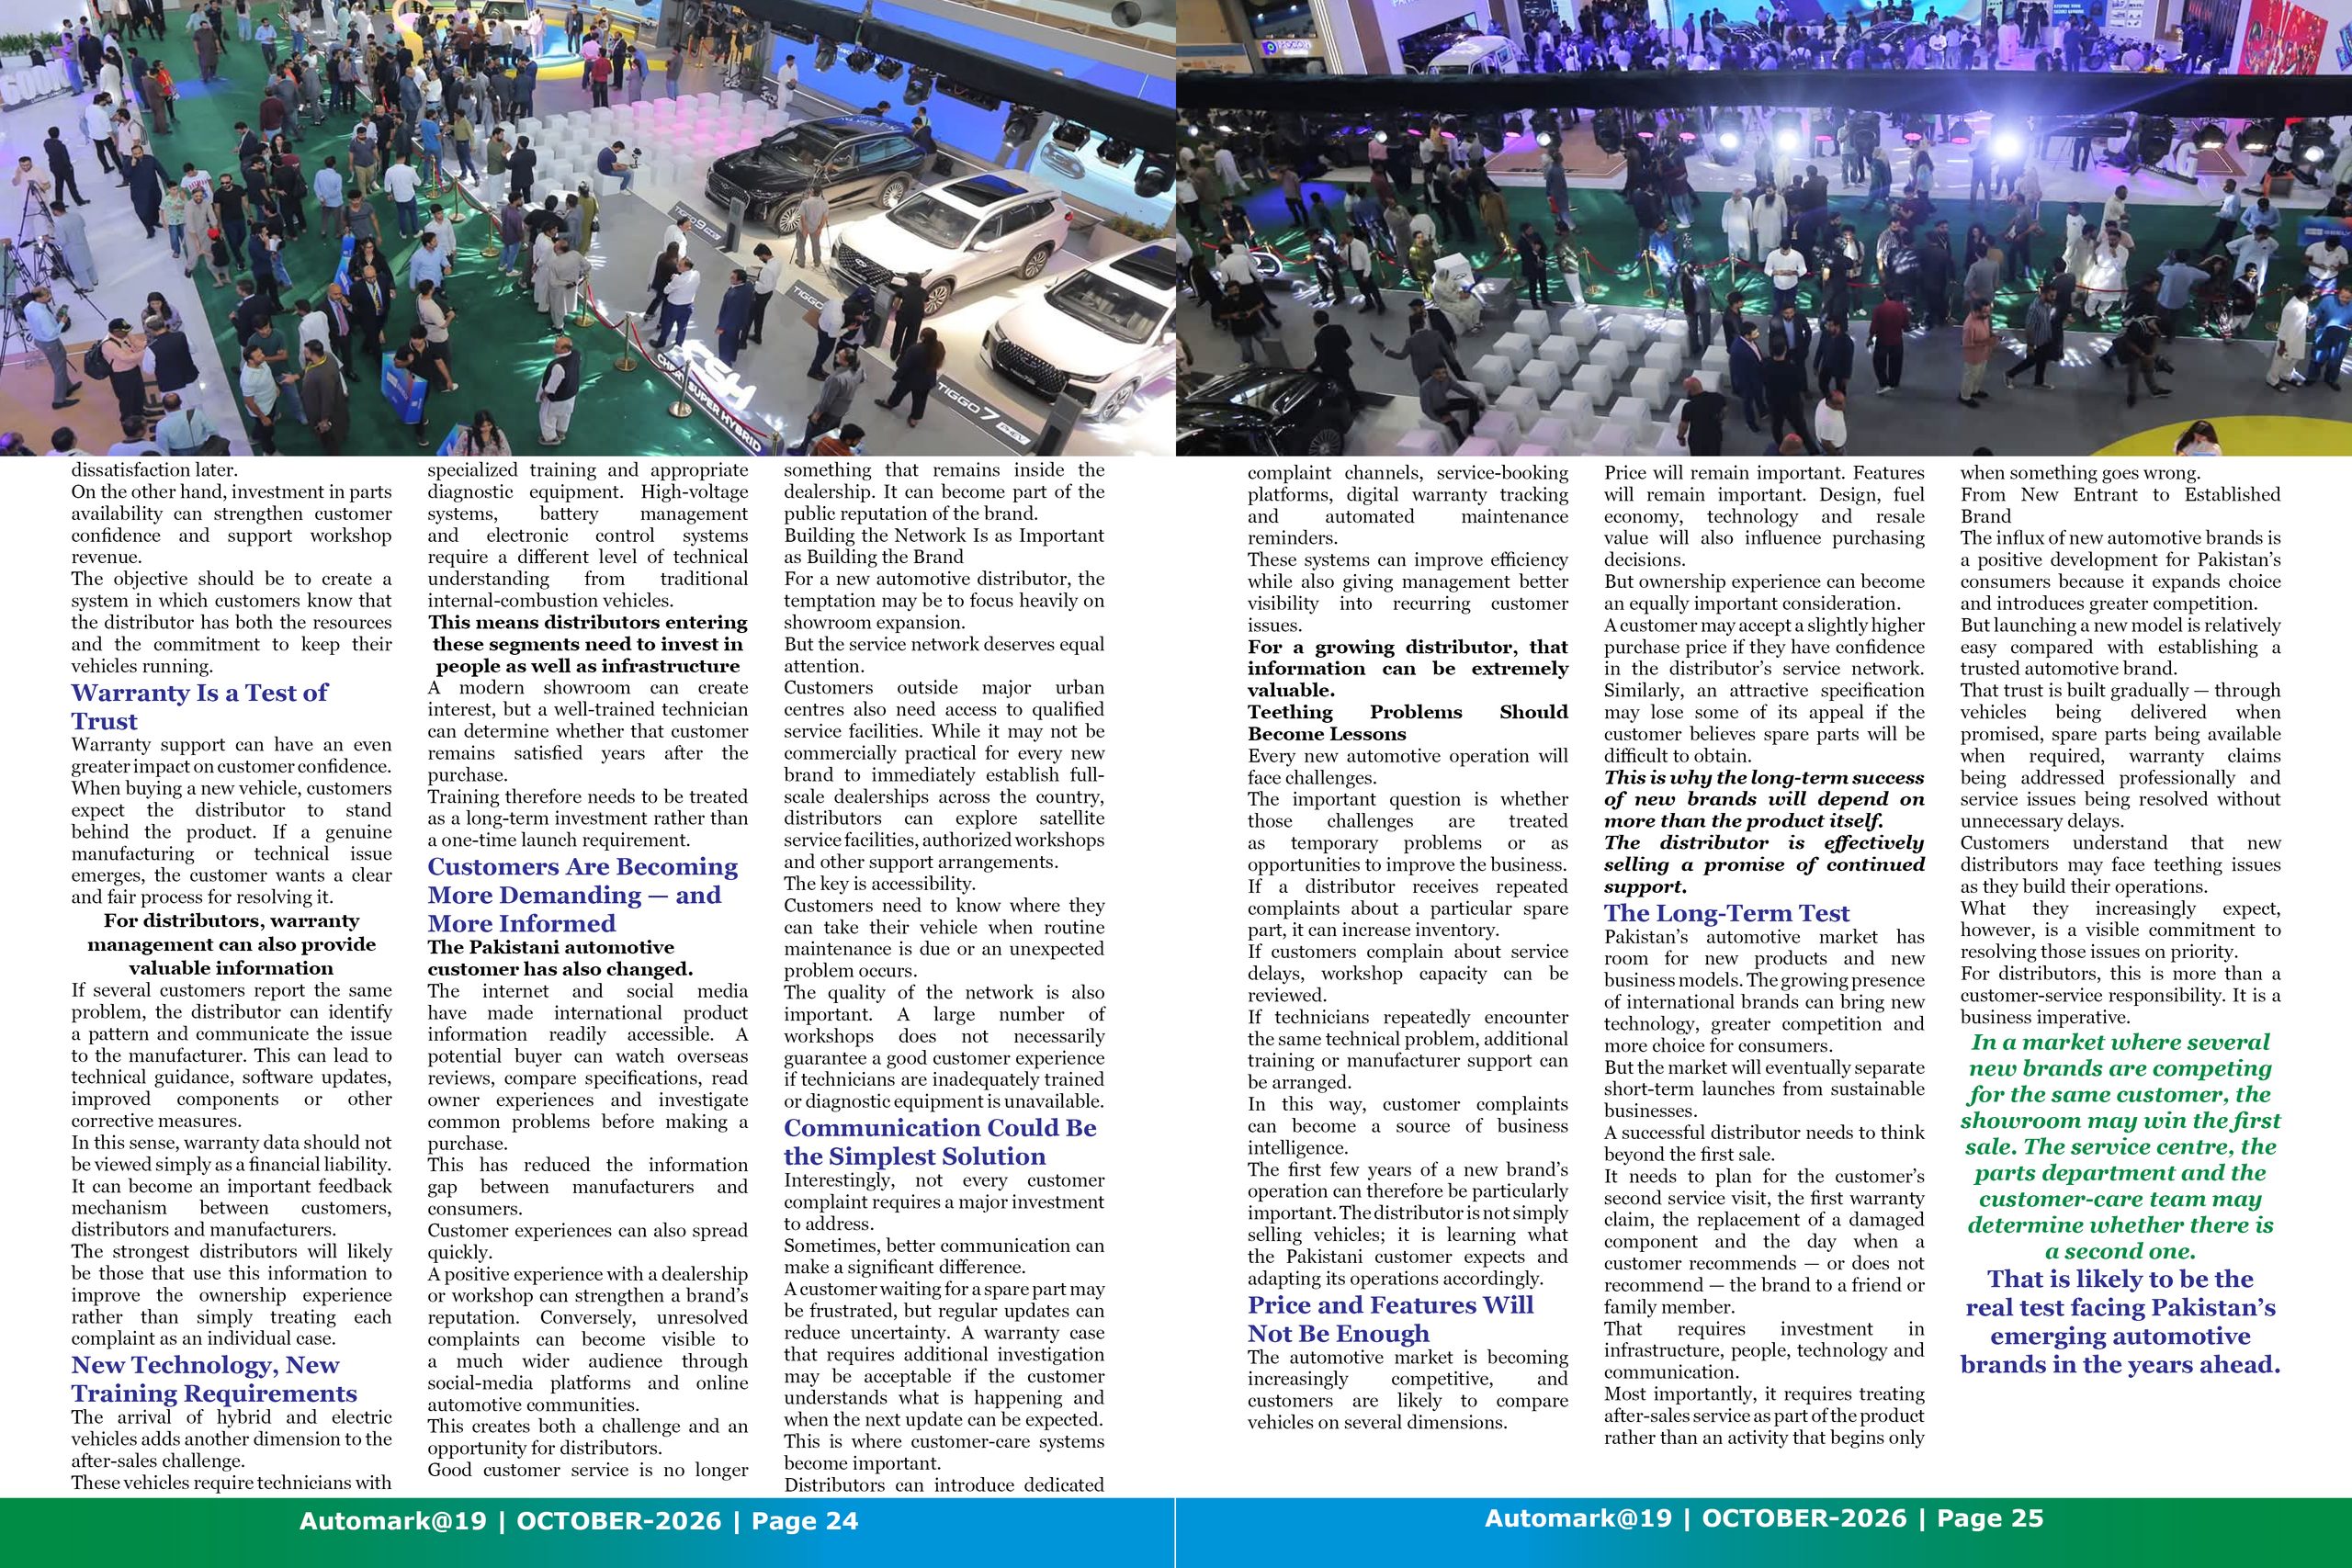
A growing number of local distributors are introducing new international brands and vehicle models, giving consumers access to products that were previously unavailable in the country. Chinese automotive brands, hybrid vehicles, electric cars, SUVs and feature-rich models are increasingly finding space in local showrooms.
For customers, the development offers greater choice. For distributors, it represents a potentially significant business opportunity.
But there is another side to this expansion.
The success of a new automotive brand in Pakistan will not be determined by its launch event, showroom presence or specification sheet alone. Increasingly, customers are asking a more practical question: What happens after I buy the car?
That question brings delivery timelines, spare-parts availability, warranty claims, service quality and technical support into sharp focus.
For new entrants, these areas could ultimately prove just as important as pricing and product features.
A Market With More Choices
For decades, Pakistan’s automobile market was dominated by a limited number of established manufacturers. Customers generally knew where to go for a new vehicle, where to have it serviced and where to find spare parts.
The emergence of new distributors is changing that equation.
Today, customers can consider a much wider range of vehicles, from compact cars and crossovers to larger SUVs, hybrids and electric vehicles. Many of these models come with technology and features that are designed to compete strongly in international markets.
This is creating a more competitive environment.
For consumers, competition can mean greater choice and pressure on manufacturers and distributors to offer better products, pricing and customer service.
For distributors, however, entering the market involves much more than importing vehicles and establishing dealerships.
A successful automotive operation requires an ecosystem.
That ecosystem includes inventory management, logistics, workshops, trained technicians, diagnostic equipment, spare-parts warehouses, warranty systems, customer-care operations and a network capable of supporting customers after the sale.
Building all of this takes time and investment.
The Real Business Begins After the Sale
The initial vehicle sale generates revenue, but the long-term relationship with the customer can determine the future of the brand.
Every vehicle sold creates a potential stream of future business through scheduled maintenance, replacement parts, warranty support and eventual vehicle upgrades or replacement.
This makes after-sales service more than simply a cost centre. It is an important part of customer retention and brand building.
For a new distributor, the challenge is particularly significant.
An established automotive company may already have years of experience, trained staff, supplier relationships and a developed service network. A new entrant has to build many of these capabilities from the ground up.
This is where early “teething issues” can emerge.
Customers may experience delays in vehicle deliveries, limited availability of certain parts or longer-than-expected waiting periods at service facilities.
Such challenges are not necessarily unusual for a new operation. What matters is how the distributor responds.
Delivery Delays Can Damage Early Confidence
Vehicle delivery is one of the first major tests of a distributor’s relationship with its customers.
When a customer books a vehicle, the delivery date becomes part of the purchase decision. Buyers may arrange financing, sell their existing vehicle or make other personal commitments based on the expected delivery schedule.
A delay can therefore have consequences beyond simple inconvenience.
Supply-chain challenges can arise for many reasons. Imported vehicles may be affected by shipping schedules, customs procedures, production planning, foreign-exchange constraints or other logistical factors.
The commercial challenge for distributors is to manage these uncertainties without losing customer confidence.
Communication is critical.
If a delivery is delayed, customers generally want an honest explanation and a realistic revised timeline. Repeatedly providing dates that cannot be met can be more damaging than acknowledging a delay from the beginning.
For a new brand trying to establish its reputation, transparency can be an important competitive asset.
After-Sales Support Will Separate the Brands
The growing number of brands in Pakistan means that customers will increasingly compare not only vehicles but also ownership experiences.
A vehicle can have an attractive price and an impressive list of features, but if the customer struggles to get it serviced or cannot obtain a required spare part, the initial attraction can quickly fade.
This makes after-sales support one of the most important areas for distributors to address.
A capable after-sales operation requires trained technicians, appropriate diagnostic equipment, genuine parts and clear procedures for warranty and technical complaints.
It also requires management attention.
When a customer reports a problem, there needs to be a process for registering the complaint, identifying its cause, determining responsibility and providing a solution within a reasonable timeframe.
For new brands, these systems are especially important because early customer experiences can shape the perception of the entire brand.
Spare Parts: A Critical Piece of the Puzzle
Spare-parts availability remains one of the most closely watched issues for customers considering relatively new automotive brands.
The concern is straightforward: if something goes wrong, how long will the vehicle remain off the road?
For routine maintenance items, distributors should ideally maintain adequate local inventory. For less common components, there needs to be an efficient ordering and logistics system.
This is not merely a customer-service issue. It is also a business-planning issue.
A distributor that sells thousands of vehicles without adequately planning its parts inventory could find itself dealing with growing customer dissatisfaction later.
On the other hand, investment in parts availability can strengthen customer confidence and support workshop revenue.
The objective should be to create a system in which customers know that the distributor has both the resources and the commitment to keep their vehicles running.
Warranty Is a Test of Trust
Warranty support can have an even greater impact on customer confidence.
When buying a new vehicle, customers expect the distributor to stand behind the product. If a genuine manufacturing or technical issue emerges, the customer wants a clear and fair process for resolving it.
For distributors, warranty management can also provide valuable information.
If several customers report the same problem, the distributor can identify a pattern and communicate the issue to the manufacturer. This can lead to technical guidance, software updates, improved components or other corrective measures.
In this sense, warranty data should not be viewed simply as a financial liability.
It can become an important feedback mechanism between customers, distributors and manufacturers.
The strongest distributors will likely be those that use this information to improve the ownership experience rather than simply treating each complaint as an individual case.
New Technology, New Training Requirements
The arrival of hybrid and electric vehicles adds another dimension to the after-sales challenge.
These vehicles require technicians with specialized training and appropriate diagnostic equipment. High-voltage systems, battery management and electronic control systems require a different level of technical understanding from traditional internal-combustion vehicles.
This means distributors entering these segments need to invest in people as well as infrastructure.
A modern showroom can create interest, but a well-trained technician can determine whether that customer remains satisfied years after the purchase.
Training therefore needs to be treated as a long-term investment rather than a one-time launch requirement.
Customers Are Becoming More Demanding — and More Informed
The Pakistani automotive customer has also changed.
The internet and social media have made international product information readily accessible. A potential buyer can watch overseas reviews, compare specifications, read owner experiences and investigate common problems before making a purchase.
This has reduced the information gap between manufacturers and consumers.
Customer experiences can also spread quickly.
A positive experience with a dealership or workshop can strengthen a brand’s reputation. Conversely, unresolved complaints can become visible to a much wider audience through social-media platforms and online automotive communities.
This creates both a challenge and an opportunity for distributors.
Good customer service is no longer something that remains inside the dealership. It can become part of the public reputation of the brand.
Building the Network Is as Important as Building the Brand
For a new automotive distributor, the temptation may be to focus heavily on showroom expansion.
But the service network deserves equal attention.
Customers outside major urban centres also need access to qualified service facilities. While it may not be commercially practical for every new brand to immediately establish full-scale dealerships across the country, distributors can explore satellite service facilities, authorized workshops and other support arrangements.
The key is accessibility.
Customers need to know where they can take their vehicle when routine maintenance is due or an unexpected problem occurs.
The quality of the network is also important. A large number of workshops does not necessarily guarantee a good customer experience if technicians are inadequately trained or diagnostic equipment is unavailable.
Communication Could Be the Simplest Solution
Interestingly, not every customer complaint requires a major investment to address.
Sometimes, better communication can make a significant difference.
A customer waiting for a spare part may be frustrated, but regular updates can reduce uncertainty. A warranty case that requires additional investigation may be acceptable if the customer understands what is happening and when the next update can be expected.
This is where customer-care systems become important.
Distributors can introduce dedicated complaint channels, service-booking platforms, digital warranty tracking and automated maintenance reminders.
These systems can improve efficiency while also giving management better visibility into recurring customer issues.
For a growing distributor, that information can be extremely valuable.
Teething Problems Should Become Lessons
Every new automotive operation will face challenges.
The important question is whether those challenges are treated as temporary problems or as opportunities to improve the business.
If a distributor receives repeated complaints about a particular spare part, it can increase inventory.
If customers complain about service delays, workshop capacity can be reviewed.
If technicians repeatedly encounter the same technical problem, additional training or manufacturer support can be arranged.
In this way, customer complaints can become a source of business intelligence.
The first few years of a new brand’s operation can therefore be particularly important. The distributor is not simply selling vehicles; it is learning what the Pakistani customer expects and adapting its operations accordingly.
Price and Features Will Not Be Enough
The automotive market is becoming increasingly competitive, and customers are likely to compare vehicles on several dimensions.
Price will remain important. Features will remain important. Design, fuel economy, technology and resale value will also influence purchasing decisions.
But ownership experience can become an equally important consideration.
A customer may accept a slightly higher purchase price if they have confidence in the distributor’s service network. Similarly, an attractive specification may lose some of its appeal if the customer believes spare parts will be difficult to obtain.
This is why the long-term success of new brands will depend on more than the product itself.
The distributor is effectively selling a promise of continued support.
The Long-Term Test
Pakistan’s automotive market has room for new products and new business models. The growing presence of international brands can bring new technology, greater competition and more choice for consumers.
But the market will eventually separate short-term launches from sustainable businesses.
A successful distributor needs to think beyond the first sale.
It needs to plan for the customer’s second service visit, the first warranty claim, the replacement of a damaged component and the day when a customer recommends — or does not recommend — the brand to a friend or family member.
That requires investment in infrastructure, people, technology and communication.
Most importantly, it requires treating after-sales service as part of the product rather than an activity that begins only when something goes wrong.
From New Entrant to Established Brand
The influx of new automotive brands is a positive development for Pakistan’s consumers because it expands choice and introduces greater competition.
But launching a new model is relatively easy compared with establishing a trusted automotive brand.
That trust is built gradually — through vehicles being delivered when promised, spare parts being available when required, warranty claims being addressed professionally and service issues being resolved without unnecessary delays.
Customers understand that new distributors may face teething issues as they build their operations.
What they increasingly expect, however, is a visible commitment to resolving those issues on priority.
For distributors, this is more than a customer-service responsibility. It is a business imperative.
In a market where several new brands are competing for the same customer, the showroom may win the first sale. The service centre, the parts department and the customer-care team may determine whether there is a second one.
That is likely to be the real test facing Pakistan’s emerging automotive brands in the years ahead.
This exclusive article has been published in Automark’s October-2026 printed and digital edition. Written by Aqeel Bashir